The end of an earnings season can be a great time to discover new stocks and assess how companies are handling the current business environment. Let’s take a look at how LKQ (NASDAQ: LKQ) and the rest of the consumer discretionary - specialized consumer services stocks fared in Q2.
The Consumer Discretionary sector, by definition, is made up of companies selling non-essential goods and services. When economic conditions deteriorate or tastes shift, consumers can easily cut back or eliminate these purchases. For long-term investors with five-year holding periods, this creates a structural challenge: the sector is inherently hit-driven, with low switching costs and fickle customers. As a result, only a handful of companies can reliably grow demand and compound earnings over long periods, which is why our bar is high and High Quality ratings are rare. Some consumer discretionary companies don’t fall neatly into a category because their products or services are unique. Although their offerings may be niche, these companies have often found more efficient or technology-enabled ways of doing or selling something that has existed for a while. Technology can be a double-edged sword, though, as it may lower the barriers to entry for new competitors and allow them to serve customers better.
The 10 consumer discretionary - specialized consumer services stocks we track reported a slower Q2. As a group, revenues missed analysts’ consensus estimates by 0.7% while next quarter’s revenue guidance was 1% above.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 9.4% since the latest earnings results.
LKQ (NASDAQ: LKQ)
A global distributor of vehicle parts and accessories, LKQ (NASDAQ: LKQ) offers its customers a comprehensive selection of high-quality, affordably priced automobile products.
LKQ reported revenues of $3.41 billion, down 3% year on year. This print fell short of analysts’ expectations by 2.3%. Overall, it was a softer quarter for the company with full-year EPS guidance missing analysts’ expectations and a significant miss of analysts’ EPS estimates.
"Our second‑quarter performance reflected solid execution across our North America and Specialty segments. North America returned to positive organic growth for the first time in nine quarters, driven by record alternative-parts utilization of over 40%, moderating insurance premiums that were negative in May and June, and continued sequential improvement in repairable claims. Specialty also delivered growth despite a challenging end‑market environment and continued macro‑economic pressure on consumers. Europe fell short of expectations, with results affected by the ERP implementation in Germany. Outside of the ERP impact, the team delivered substantial cost reductions that largely offset the lower volumes we witnessed in the UK and Benelux regions. Overall, the fundamentals of our business are improving, and as market conditions continue to recover, we expect those operational gains to translate into stronger financial performance and profitability in the quarters ahead," commented Justin Jude, President and Chief Executive Officer.
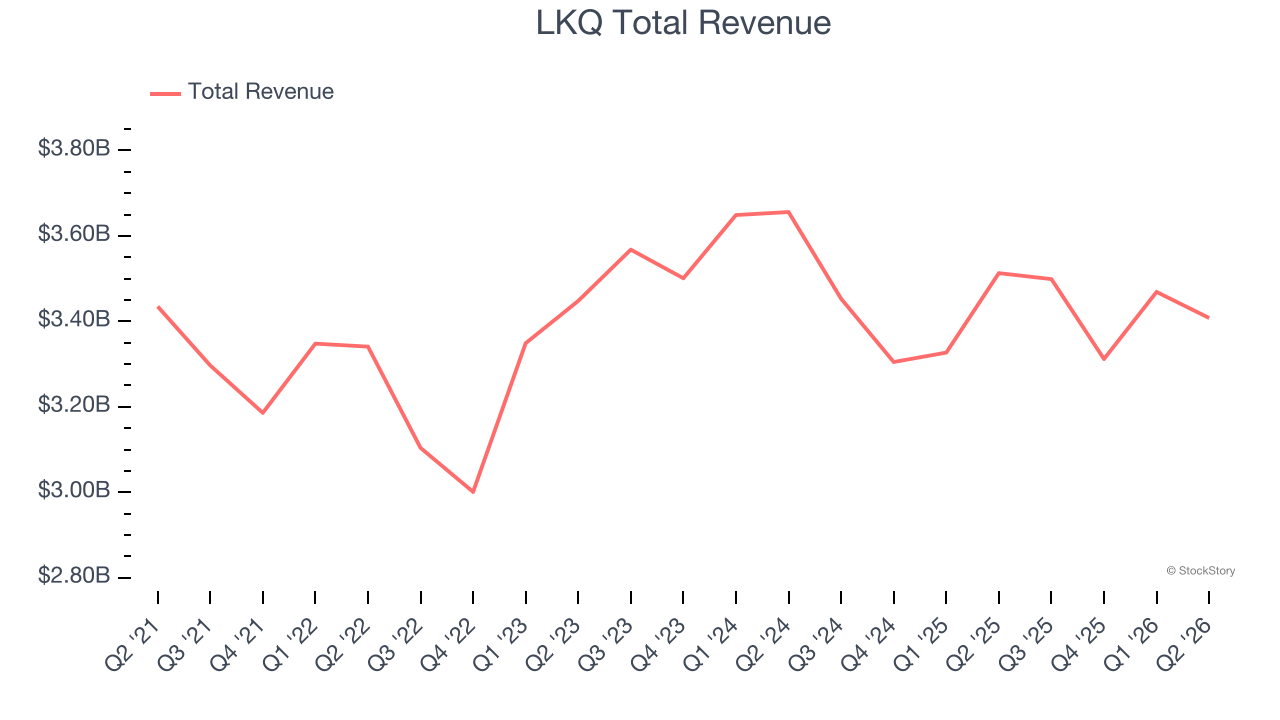
The market seems disappointed with the results as the stock is down 10.8% since reporting and currently trades at $23.54.
Read our full report on LKQ here, it’s free.
Best Q2: H&R Block (NYSE: HRB)
Founded in 1955 by brothers Henry W. Bloch and Richard A. Bloch, H&R Block (NYSE: HRB) is a tax preparation company offering professional tax assistance and financial solutions to individuals and small businesses.
H&R Block reported revenues of $1.14 billion, up 3% year on year, outperforming analysts’ expectations by 2.5%. The business had a very strong quarter with full-year revenue guidance beating analysts’ expectations and full-year EBITDA guidance beating analysts’ expectations.
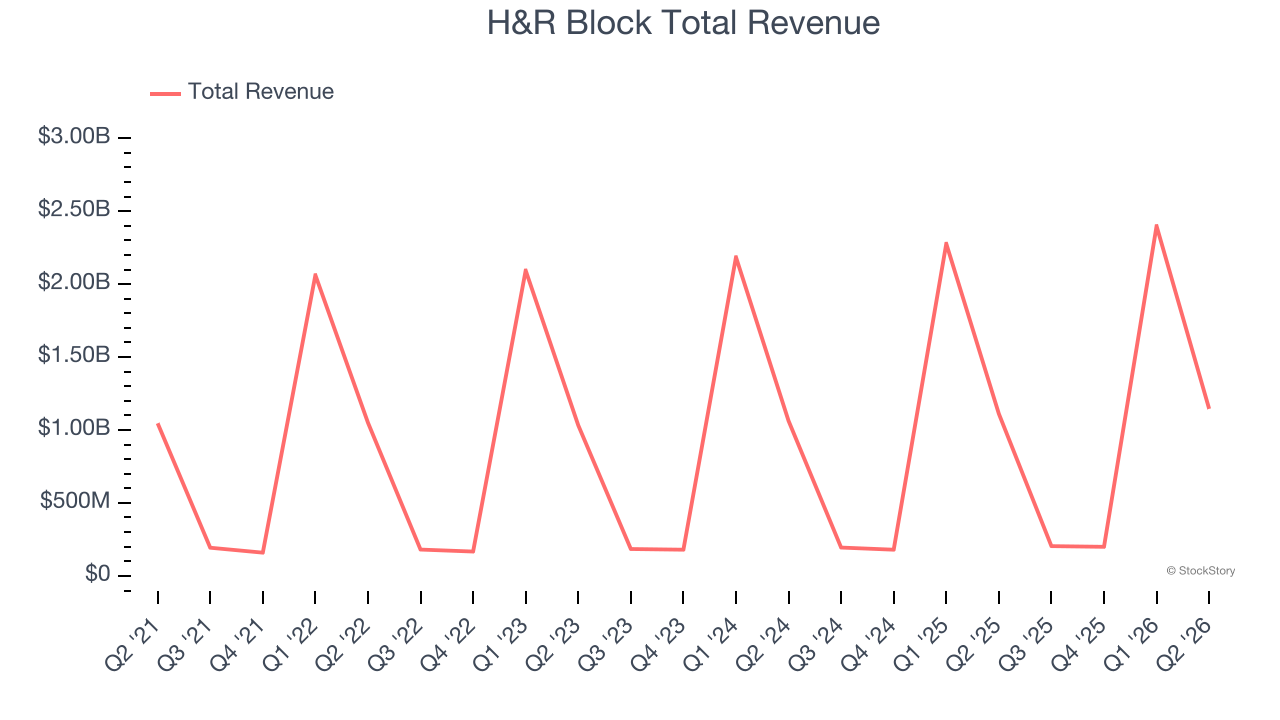
H&R Block scored the biggest analyst estimate beat and highest full-year guidance raise in the group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 1.8% since reporting. It currently trades at $45.84.
Is now the time to buy H&R Block? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Matthews (NASDAQ: MATW)
Originally a death care company, Matthews International (NASDAQ: MATW) is a diversified company offering ceremonial services, brand solutions and industrial technologies.
Matthews reported revenues of $246 million, down 29.6% year on year, falling short of analysts’ expectations by 7%. It was a disappointing quarter as it posted a significant miss of analysts’ EPS estimates and full-year EBITDA guidance missing analysts’ expectations.
Matthews delivered the weakest performance against analyst estimates and slowest revenue growth of the whole group. As expected, the stock is down 27.3% since the results and currently trades at $20.10.
Read our full analysis of Matthews’s results here.
Carriage Services (NYSE: CSV)
Established in 1991, Carriage Services (NYSE: CSV) is a provider of funeral and cemetery services in the United States.
Carriage Services reported revenues of $102.9 million, flat year on year. This print lagged analysts’ expectations by 5.5%. It was a slower quarter as it also recorded a significant miss of analysts’ EPS estimates and full-year revenue guidance slightly missing analysts’ expectations.
The stock is down 21.9% since reporting and currently trades at $32.32.
Read our full, actionable report on Carriage Services here, it’s free.
Frontdoor (NASDAQ: FTDR)
Established in 2018 as a spin-off from ServiceMaster Global Holdings, Frontdoor (NASDAQ: FTDR) is a provider of home warranty and service plans.
Frontdoor reported revenues of $645 million, up 4.5% year on year. This number was in line with analysts’ expectations. Overall, it was a strong quarter as it also recorded full-year EBITDA guidance topping analysts’ expectations and a beat of analysts’ EPS estimates.
Frontdoor pulled off the fastest revenue growth among its peers. The stock is up 4.8% since reporting and currently trades at $80.08.
Read our full, actionable report on Frontdoor here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Growth Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.