The end of the earnings season is always a good time to take a step back and see who shined (and who didn’t). Let’s take a look at how sales and marketing software stocks fared in Q1, starting with Upland Software (NASDAQ: UPLD).
The Internet and the exploding amount of data have transformed how businesses interact with, market to, and transact with their customers. Personalization of offerings, e-commerce, targeted advertising and data-empowered sales teams are now table stakes for modern businesses, and sales and marketing software providers are becoming the tools of evolving customer interaction.
The 18 sales and marketing software stocks we track reported a mixed Q1. As a group, revenues beat analysts’ consensus estimates by 1.4% while next quarter’s revenue guidance was 1.3% below.
In light of this news, share prices of the companies have held steady as they are up 4.9% on average since the latest earnings results.
Upland Software (NASDAQ: UPLD)
Operating under the mantra "land and expand," Upland Software (NASDAQ: UPLD) provides cloud-based applications that help organizations manage projects, workflows, and digital transformation across various business functions.
Upland Software reported revenues of $48.69 million, down 23.5% year on year. This print was in line with analysts’ expectations, but overall, it was a disappointing quarter for the company with full-year EBITDA guidance missing analysts’ expectations significantly and revenue guidance for next quarter missing analysts’ expectations significantly.
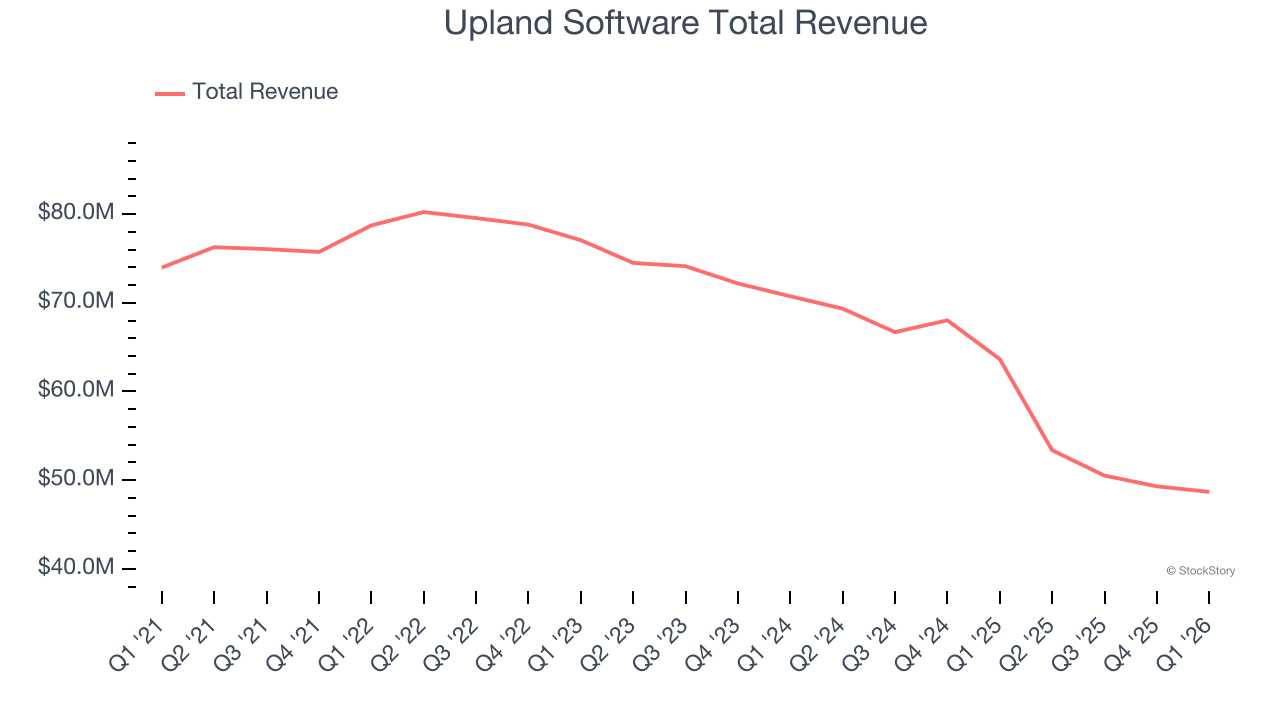
Upland Software delivered the slowest revenue growth among its peers. The market seems disappointed with the results as the stock is down 37.5% since reporting and currently trades at $3.91.
Read our full report on Upland Software here, it’s free.
Best Q1: PubMatic (NASDAQ: PUBM)
Powering billions of daily ad impressions across the open internet, PubMatic (NASDAQ: PUBM) operates a technology platform that helps publishers maximize revenue from their digital advertising inventory while giving advertisers more control and transparency.
PubMatic reported revenues of $78.59 million, up 10.5% year on year, outperforming analysts’ expectations by 13.7%. The business had an incredible quarter with EBITDA guidance for next quarter exceeding analysts’ expectations and revenue guidance for next quarter exceeding analysts’ expectations.
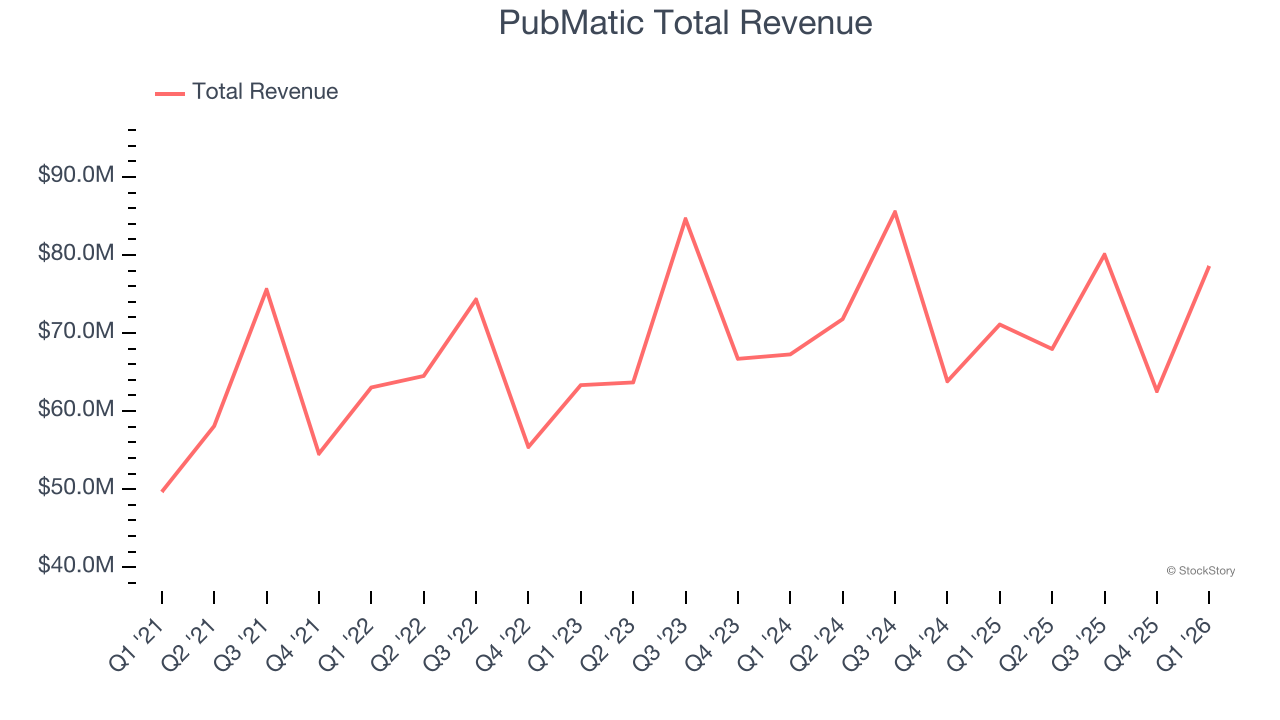
PubMatic scored the biggest analyst estimate beat and highest guidance raise in the group. The market seems happy with the results as the stock is up 24.4% since reporting. It currently trades at $16.77.
Is now the time to buy PubMatic? Access our full analysis of the earnings results here, it’s free.
DoubleVerify (NYSE: DV)
Using advanced analytics to evaluate over 17 billion digital ad transactions daily, DoubleVerify (NYSE: DV) provides AI-powered technology that verifies digital ads are viewable, fraud-free, brand-suitable, and displayed in the intended geographic location.
DoubleVerify reported revenues of $193.8 million, up 2.5% year on year, falling short of analysts’ expectations by 4.2%. It was a disappointing quarter, leaving some shareholders looking for more.
Interestingly, the stock is up 15.1% since the results and currently trades at $13.48.
Read our full analysis of DoubleVerify’s results here.
Freshworks (NASDAQ: FRSH)
Starting as a customer service solution before expanding into a comprehensive software suite, Freshworks (NASDAQ: FRSH) provides AI-powered software-as-a-service solutions that help companies manage customer service, IT support, sales, and marketing functions.
Freshworks reported revenues of $237.4 million, up 16% year on year. This result beat analysts’ expectations by 1.6%. It was a strong quarter as it also produced a solid beat of analysts’ adjusted operating income estimates and full-year EPS guidance exceeding analysts’ expectations.
The company added 268 enterprise customers paying more than $5,000 annually to reach a total of 25,356. The stock is up 4.9% since reporting and currently trades at $12.63.
Read our full, actionable report on Freshworks here, it’s free.
LiveRamp (NYSE: RAMP)
Serving as the digital middleman in an increasingly privacy-conscious world, LiveRamp (NYSE: RAMP) provides technology that helps companies securely share and connect their customer data with trusted partners while maintaining privacy compliance.
LiveRamp reported revenues of $214 million, up 9.8% year on year. This print surpassed analysts’ expectations by 0.9%. Overall, it was a strong quarter as it also logged an impressive beat of analysts’ adjusted operating income estimates.
The company lost 1 enterprise customers paying more than $1 million annually and ended up with a total of 132. The stock is flat since reporting and currently trades at $37.61.
Read our full, actionable report on LiveRamp here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Growth Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.