Looking back on industrial distributors stocks’ Q2 earnings, we examine this quarter’s best and worst performers, including Watsco (NYSE: WSO) and its peers.
Supply chain and inventory management are themes that grew in focus after COVID wreaked havoc on the global movement of raw materials and components. Distributors that boast a reliable selection of products–everything from hardhats and fasteners for jet engines to ceiling systems–and quickly deliver goods to customers can benefit from this theme. While e-commerce hasn’t disrupted industrial distribution as much as consumer retail, it is still a real threat, forcing investment in omnichannel capabilities to better interact with customers. Additionally, distributors are at the whim of economic cycles that impact the capital spending and construction projects that can juice demand.
The 24 industrial distributors stocks we track reported a very strong Q2. As a group, revenues beat analysts’ consensus estimates by 3.7%.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 5.2% since the latest earnings results.
Weakest Q2: Watsco (NYSE: WSO)
Originally a manufacturing company, Watsco (NYSE: WSO) today only distributes air conditioning, heating, and refrigeration equipment, as well as related parts and supplies.
Watsco reported revenues of $2.10 billion, up 2.1% year on year. This print fell short of analysts’ expectations by 1.9%. Overall, it was a disappointing quarter for the company with a significant miss of analysts’ EPS estimates.
Albert H. Nahmad, Chairman and CEO said: “Our performance during the second quarter is indicative of improving end-market stability after a busy period of regulatory transitions. We are now operating in a more conventional environment in which Watsco’s scale, OEM relationships, and technology investments can add even more value.”
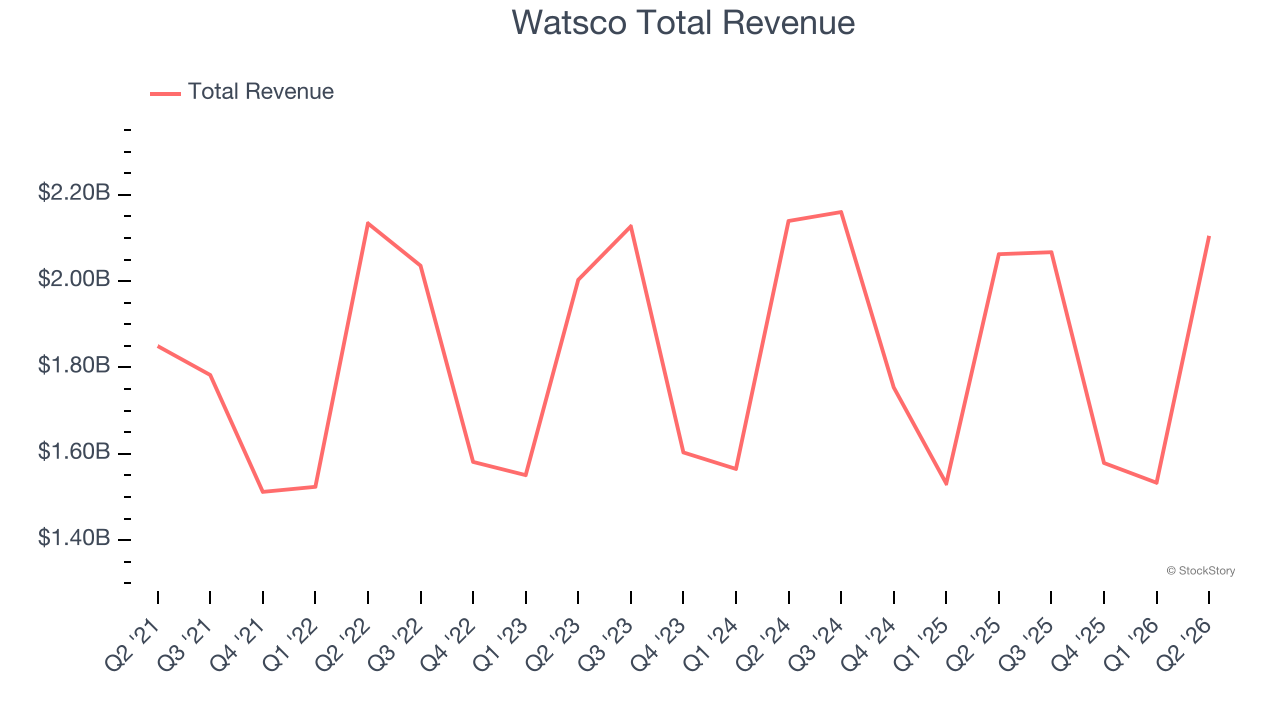
The market seems disappointed with the results as the stock is down 17.4% since reporting and currently trades at $303.57.
Read our full report on Watsco here, it’s free.
Best Q2: Transcat (NASDAQ: TRNS)
Serving the pharmaceutical, industrial manufacturing, energy, and chemical process industries, Transcat (NASDAQ: TRNS) provides measurement instruments and supplies.
Transcat reported revenues of $92.95 million, up 21.6% year on year, outperforming analysts’ expectations by 7.4%. The business had an incredible quarter with a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
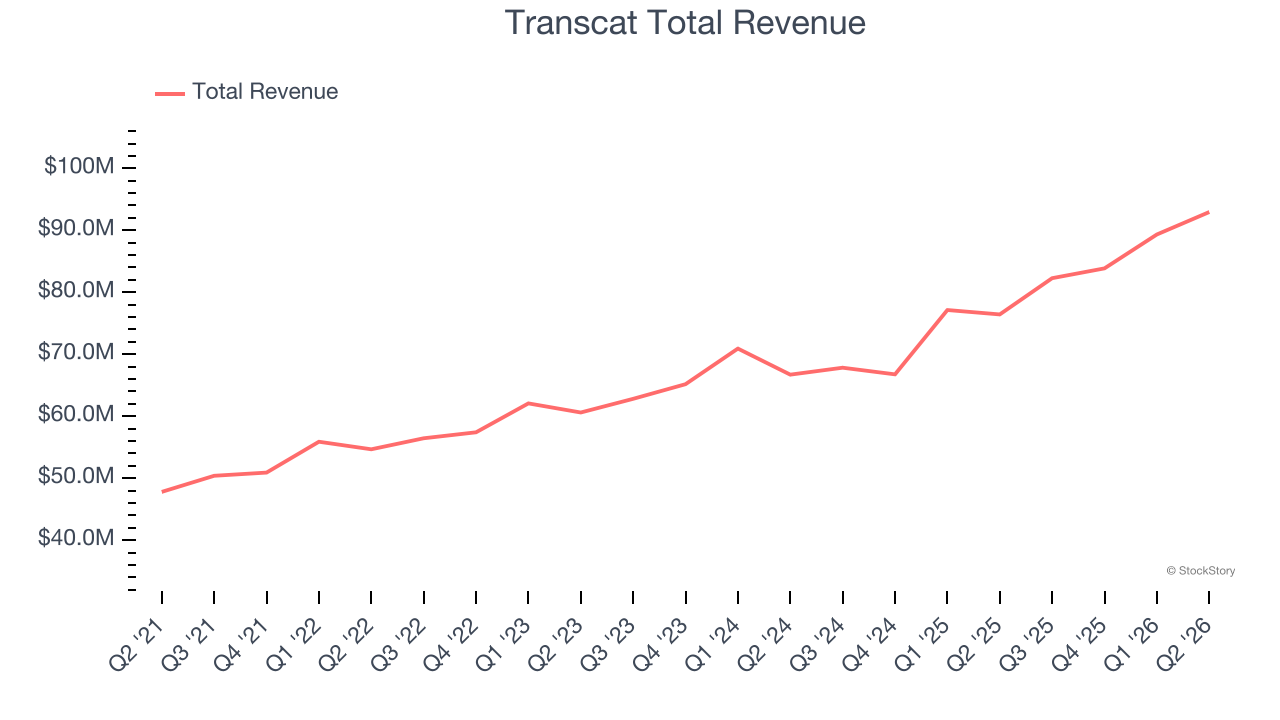
Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 11.9% since reporting. It currently trades at $81.00.
Is now the time to buy Transcat? Access our full analysis of the earnings results here, it’s free.
SiteOne (NYSE: SITE)
Known for distributing John Deere tractors and LESCO turf care products, SiteOne Landscape Supply (NYSE: SITE) provides landscaping products and services to professionals, including irrigation, lighting, and nursery supplies.
SiteOne reported revenues of $1.53 billion, up 4.7% year on year, falling short of analysts’ expectations by 0.7%. It was a softer quarter as it posted a significant miss of analysts’ EPS estimates and a miss of analysts’ EBITDA estimates.
As expected, the stock is down 15.3% since the results and currently trades at $87.67.
Read our full analysis of SiteOne’s results here.
Alta (NYSE: ALTG)
Founded in 1984, Alta Equipment Group (NYSE: ALTG) is a provider of industrial and construction equipment and services across the Midwest and Northeast United States.
Alta reported revenues of $475.5 million, down 1.2% year on year. This number came in 3.1% below analysts’ expectations. In spite of that, it was a strong quarter as it put up a beat of analysts’ EPS estimates and an impressive beat of analysts’ EBITDA estimates.
The stock is down 21.6% since reporting and currently trades at $5.78.
Read our full, actionable report on Alta here, it’s free.
Core & Main (NYSE: CNM)
Formerly a division of industrial distributor HD Supply, Core & Main (NYSE: CNM) is a provider of water, wastewater, and fire protection products and services.
Core & Main reported revenues of $2.15 billion, up 2.5% year on year. This result was in line with analysts’ expectations. However, it was a slower quarter as it recorded a significant miss of analysts’ EPS estimates and a slight miss of analysts’ EBITDA estimates.
The stock is down 6.7% since reporting and currently trades at $41.09.
Read our full, actionable report on Core & Main here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our 9 Best Market-Beating Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.