Since April 2026, Costco has been in a holding pattern, posting a small loss of 0.8% while floating around $979.55. The stock also fell short of the S&P 500’s 9.7% gain during that period.
Is now the time to buy COST? Find out in our full research report, it’s free.
Why Does COST Stock Spark Debate?
Designed to be a one-stop shop for the suburban consumer, Costco (NASDAQ: COST) is a membership-only retail chain that sells groceries, apparel, toys, and household items, often in bulk quantities.
Two Things to Like:
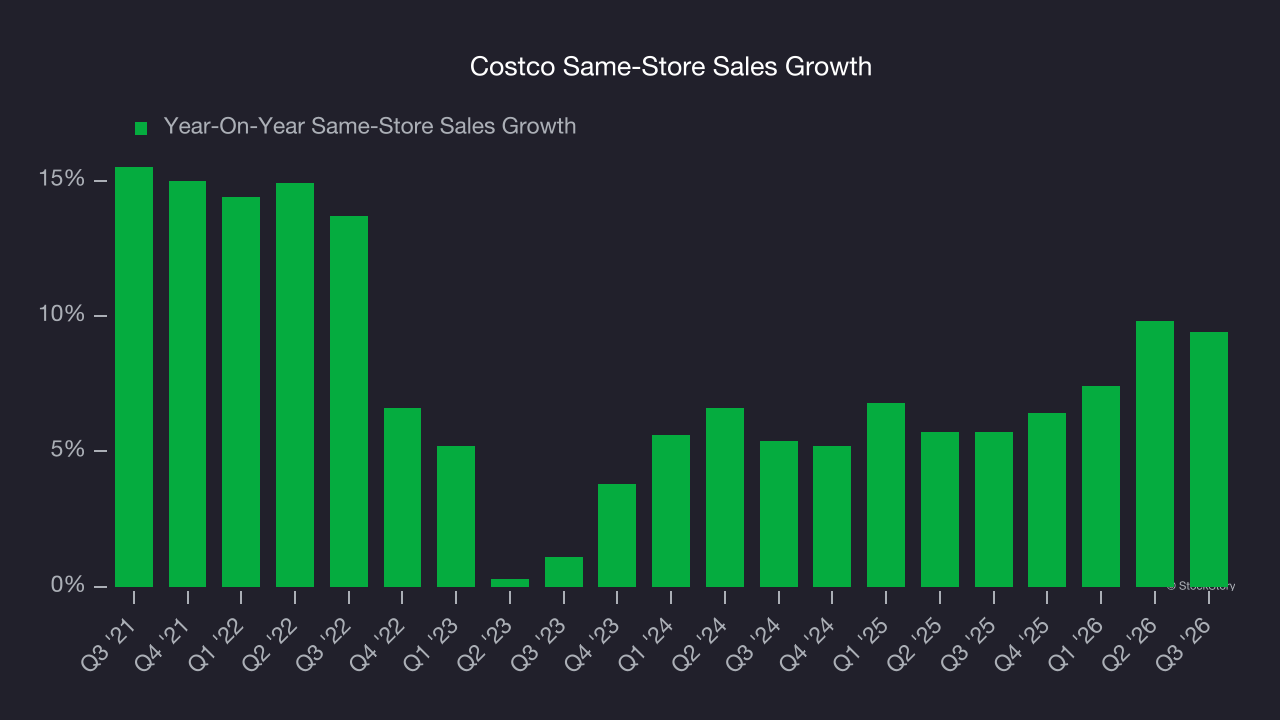
1. Surging Same-Store Sales Show Increasing Demand
Same-store sales is a key performance indicator used to measure organic growth at brick-and-mortar shops for at least a year.
Costco has been one of the most successful retailers over the last two years thanks to skyrocketing demand within its existing locations. On average, the company has posted exceptional year-on-year same-store sales growth of 7.1%.
2. Economies of Scale Give It Negotiating Leverage with Suppliers
With $303.2 billion in revenue over the past 12 months, Costco is a behemoth in the consumer retail sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices. However, its scale is a double-edged sword because there is only so much real estate to build new stores, placing a ceiling on its growth. To accelerate sales, Costco likely needs to optimize its pricing or lean into international expansion.
One Reason to Be Careful:
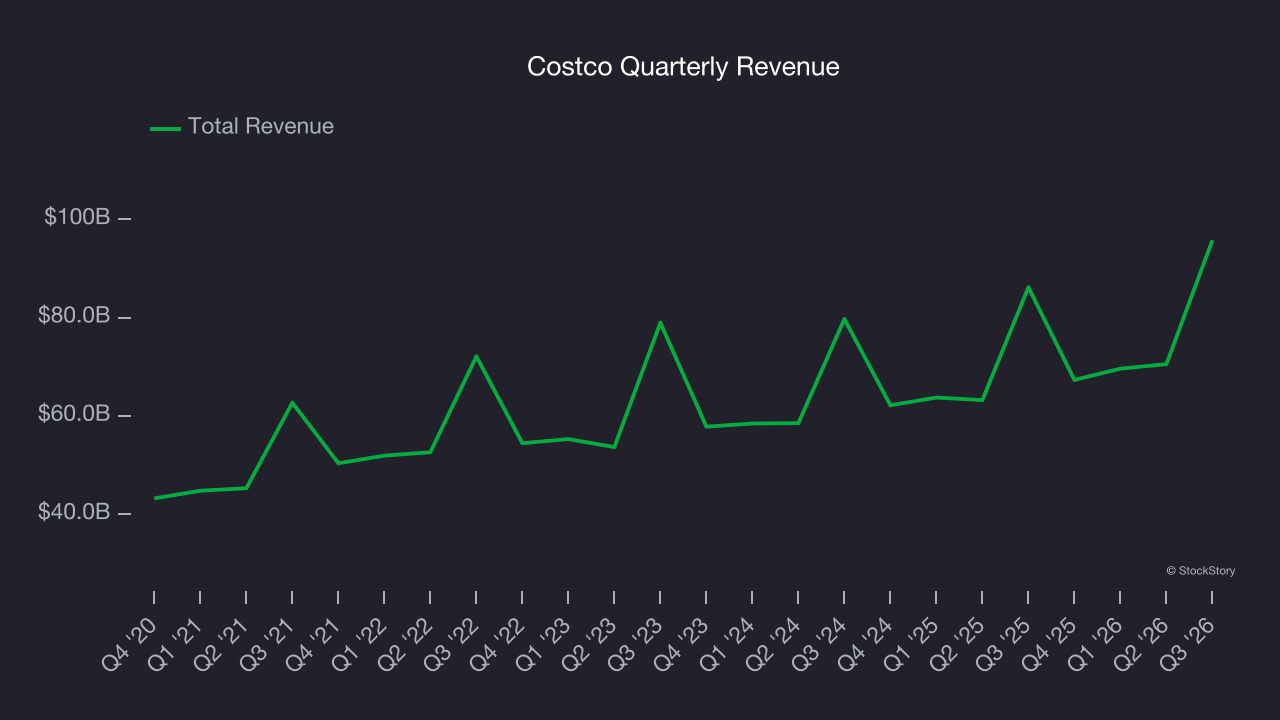
Long-Term Revenue Growth Disappoints
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Regrettably, Costco’s sales grew at a mediocre 7.8% compounded annual growth rate over the last three years. This wasn’t a great result compared to the rest of the consumer retail sector, but there are still things to like about Costco.
Final Judgment
Costco’s positive characteristics outweigh the negatives. With its shares trailing the market in recent months, the stock trades at 43× forward P/E (or $979.55 per share). Is now the time to initiate a position? See for yourself in our in-depth research report, it’s free.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.