Aerospace and defense company Boeing (NYSE: BA) met Wall Street’s revenue expectations in Q3 2026, with revenue rising 3.9% year on year to $24.19 billion. Its non-GAAP loss of $0.34 per share was 69.2% below analysts’ consensus estimates.
For more on Boeing, read our full research report, available free.
Boeing (BA) Q3 2026 highlights:
- Revenue $24.19 billion vs S&P analysts’ consensus estimates of $24.21 billion (3.9% year-on-year growth, in line)
- Adjusted EPS -$0.34 vs S&P analysts’ consensus estimates of -$0.20 (69.2% miss)
- Operating margin 1.5%, up from -20.5% in the same quarter last year
- Free cash flow margin 1.9%, similar to the same quarter last year
- Backlog $745.4 billion at quarter end, up 17.3% year on year
- Sales volumes were flat year on year
- Market capitalization $148.8 billion
"Recent milestones, including certification of the 737-7 and 737-10 and selection to design and build the Navy's sixth-generation fighter aircraft, are important steps as we continue building on our progress," said Kelly Ortberg, Boeing president and chief executive officer. "But we are not done. We remain focused on safety and quality as we redouble our efforts on Lean and disciplined execution to deliver on our commitments and build the durable performance our stakeholders expect."
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Boeing’s revenue grew at a decent 8.6% compounded annual growth rate over the last five years. Its growth was slightly above the average industrials company and shows its offerings resonate with customers.
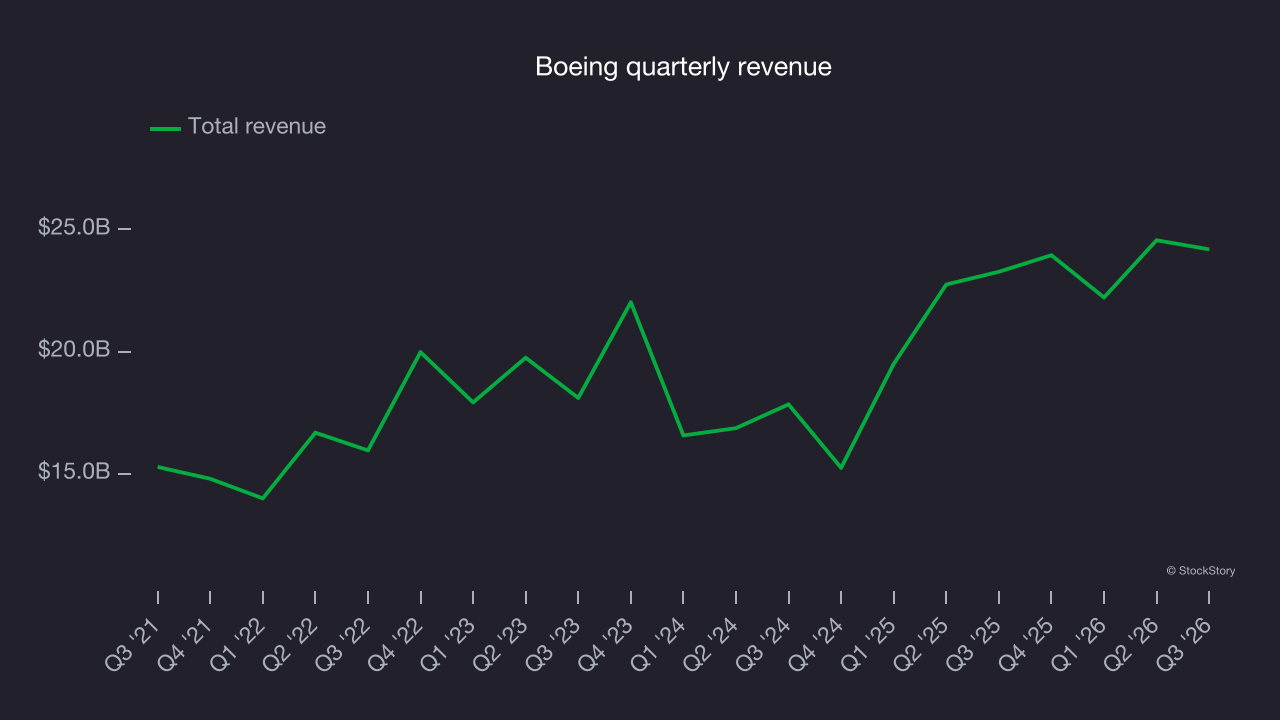
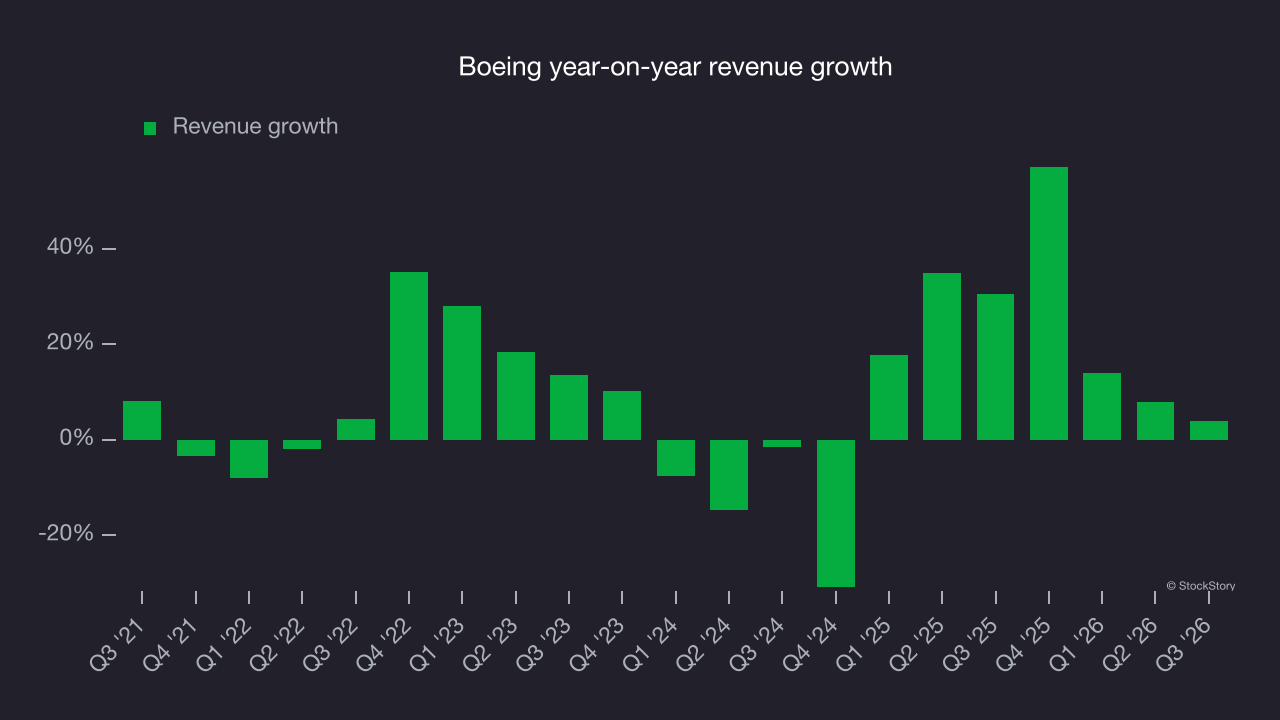
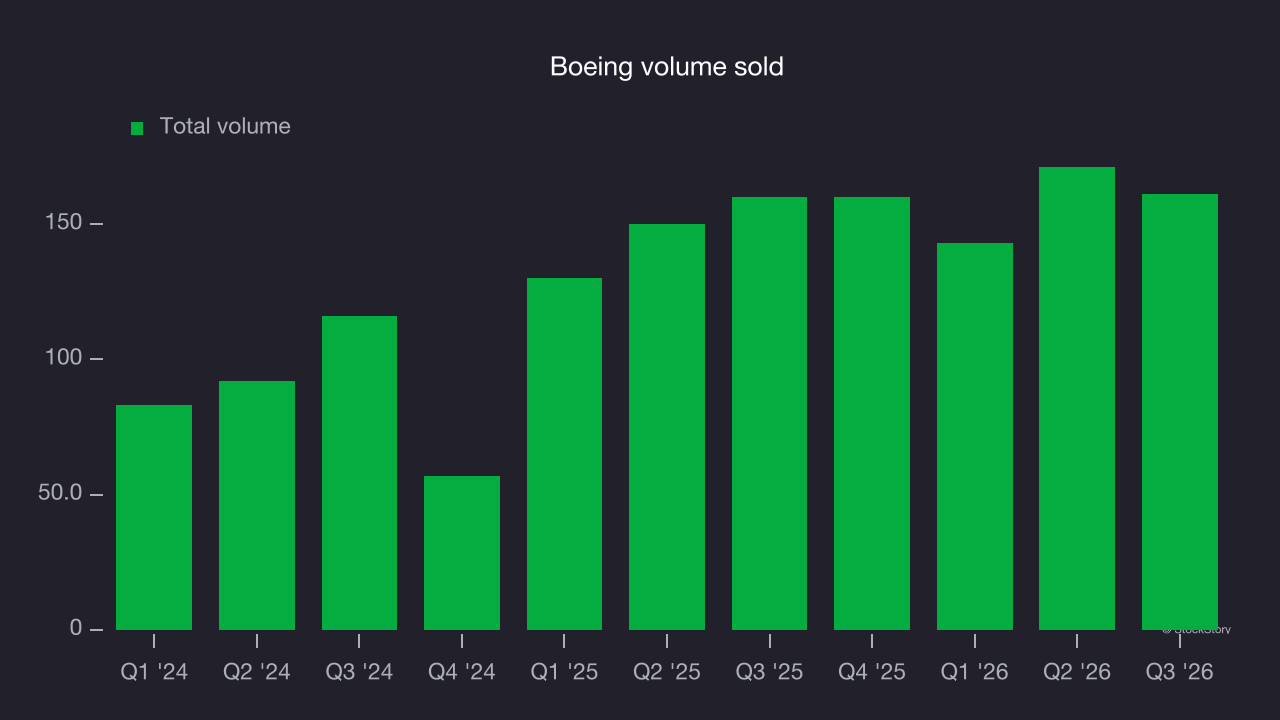
This quarter, Boeing grew its revenue by 3.9% year on year, and its $24.19 billion of revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 14.8% over the next 12 months, according to S&P, similar to its two-year rate. This is a strong growth projection for a company of its scale and indicates its newer products and services will spur better revenue performance.
Operating margin
Although Boeing was profitable at the operating level this quarter, it has generally struggled over a longer period. Its expensive cost structure has contributed to an average operating margin of negative 3.6% over the last five years. Unprofitable industrials companies warrant extra scrutiny because they can be vulnerable in a downturn.
On the positive side, Boeing’s operating margin rose by 22.2 percentage points over the last five years, as its revenue growth provided operating leverage. Still, it will take much more for the company to show consistent profitability.
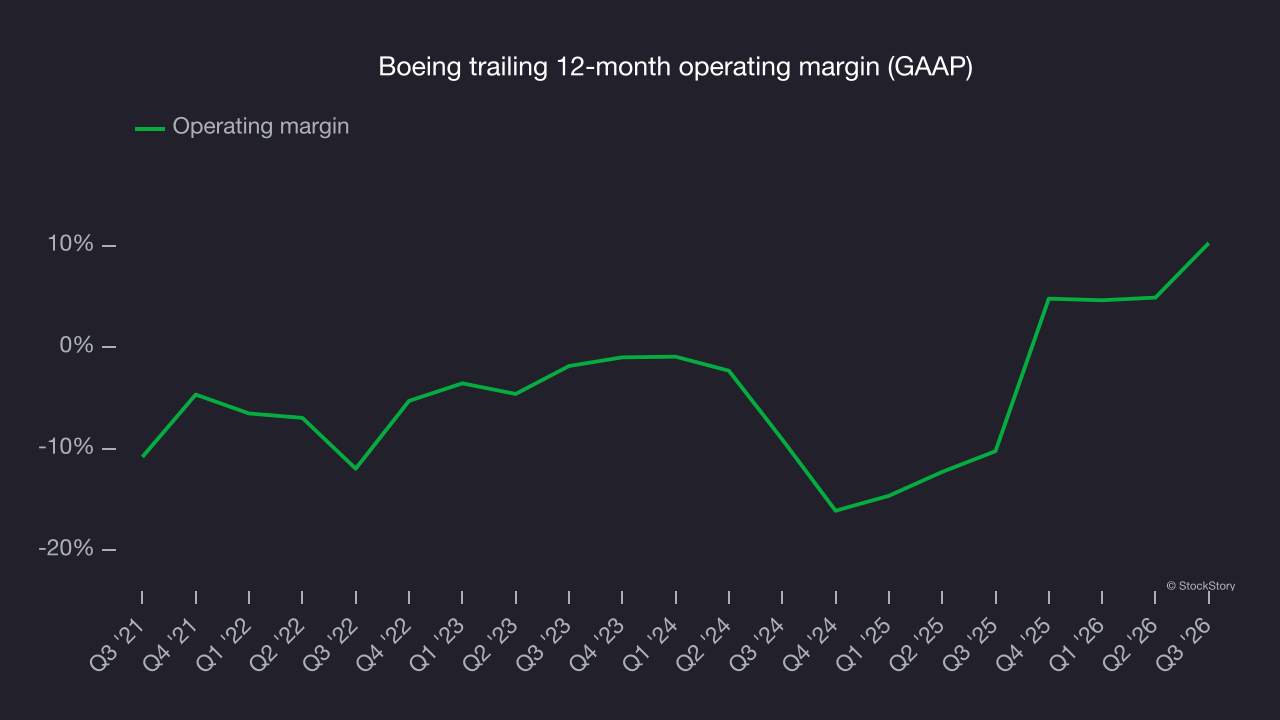
In Q3, Boeing generated an operating margin of 1.5%, up 22 percentage points year on year. This increase was a positive development and shows it operated more efficiently.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Boeing’s full-year EPS flipped from negative to positive over the last five years. This is a good sign and shows it’s at an inflection point.
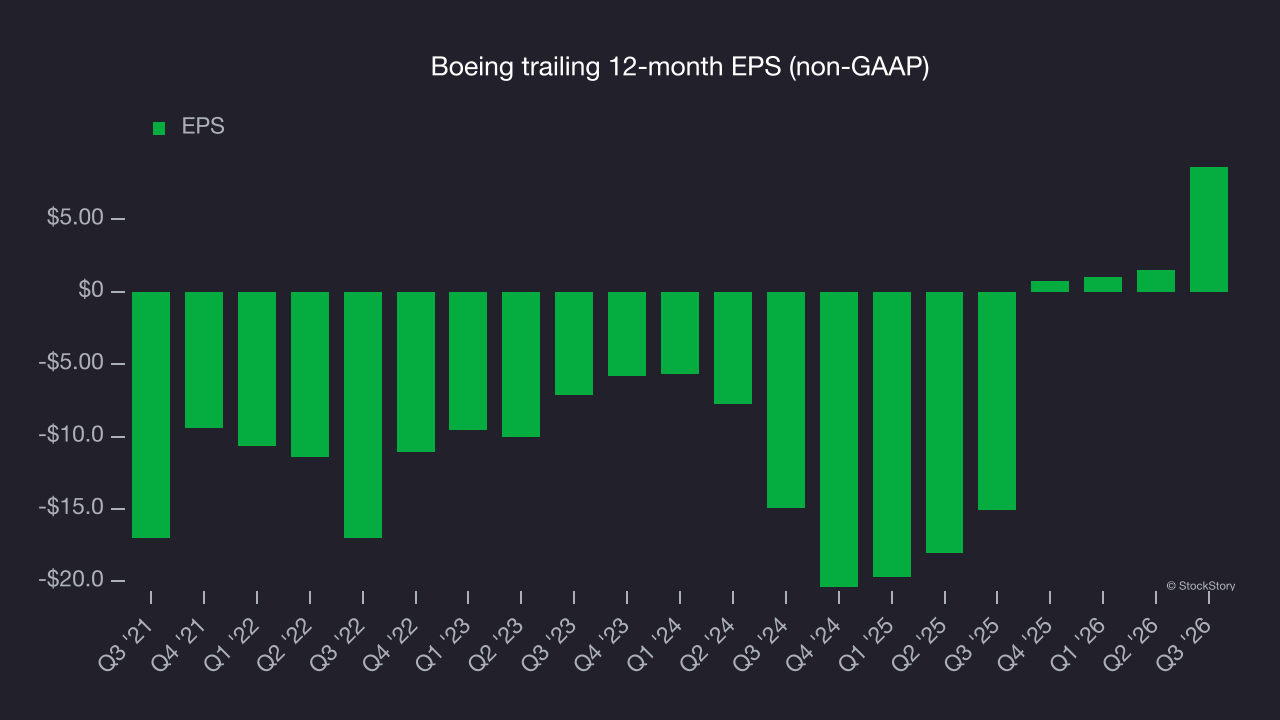
As with revenue, looking at EPS over a shorter period can reveal a change in the business.
For Boeing, its two-year annual EPS growth of 60.5% was higher than its five-year trend. Accelerating earnings growth is a positive sign, especially from an already high base.
In Q3, Boeing reported adjusted EPS of negative $0.34, which rose from negative $7.47 in the same quarter last year. Despite growing year on year, the result missed analysts’ consensus estimates, but long-term adjusted EPS growth matters more than short-term movements. Over the next 12 months, Wall Street expects Boeing’s full-year EPS to shrink by 74.7% from $8.62 to $2.18, according to S&P.
Key takeaways from Boeing’s Q3 results
Boeing’s Q3 results offered few positives, making for an underwhelming quarter. Shares remained flat at $189.65 immediately after the release.
The latest quarter is only one piece of Boeing’s longer-term business quality picture. Quality, combined with valuation, can help determine whether the stock is a buy. Read the full research report here (it’s free).