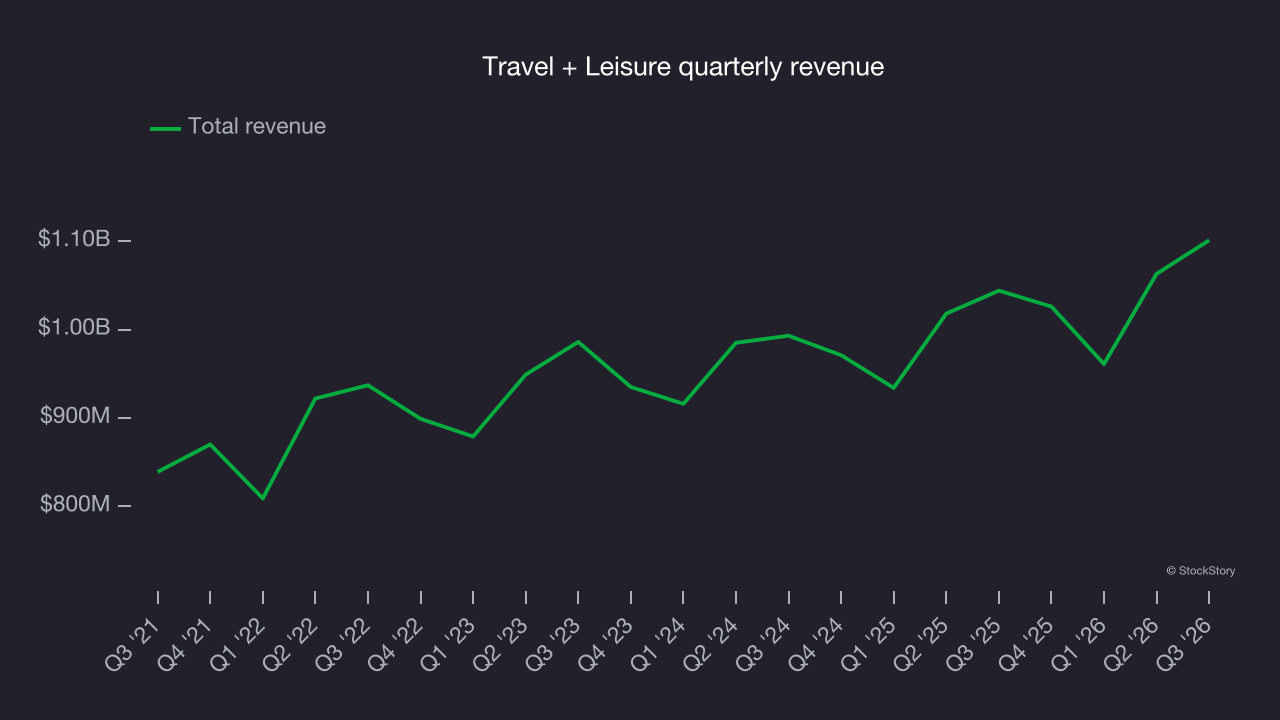
Hospitality company Travel + Leisure (NYSE: TNL) announced better-than-expected revenue in Q3 2026, with revenue up 5.5% year on year to $1.10 billion. Its non-GAAP profit of $2.21 per share was 7.5% above analysts’ consensus estimates.
For more on Travel + Leisure, read the full research report, available free.
Travel + Leisure (TNL) Q3 2026 highlights:
- Revenue $1.10 billion vs S&P analysts’ consensus estimates of $1.09 billion (5.5% year-on-year growth, 1% beat)
- Adjusted EPS $2.21 vs S&P analysts’ consensus estimates of $2.06 (7.5% beat)
- Adjusted EBITDA $283 million vs analysts’ consensus estimates of $281.8 million (25.7% margin, in line)
- EBITDA guidance $1.08 billion at the midpoint for the full year, in line with analysts’ consensus estimates
- Operating margin 17.7%, down from 20.5% in the same quarter last year
- Free cash flow margin 11.4%, down from 13.1% in the same quarter last year
- Tours conducted increased by 13,000 year on year
- Market capitalization $4.02 billion
"Year-to-date, on an adjusted basis, revenue is up 4%, EBITDA is up 8% and EPS is up 21%. These strong results validate the strategy we have outlined in recent years—consistent execution, advancing our multi-brand platform and allocating capital with discipline. With strong visibility into the balance of the year, we are confident in our ability to sustain this momentum."
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Travel + Leisure’s revenue grew at a weak 7.4% compounded annual growth rate over the last five years, falling short of the consumer discretionary sector benchmark.
Long-term growth matters most, but within consumer discretionary, a stretched historical view may miss a company riding a successful new property or trend. Travel + Leisure’s recent performance shows its demand has slowed as its annualized revenue growth of 4.1% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 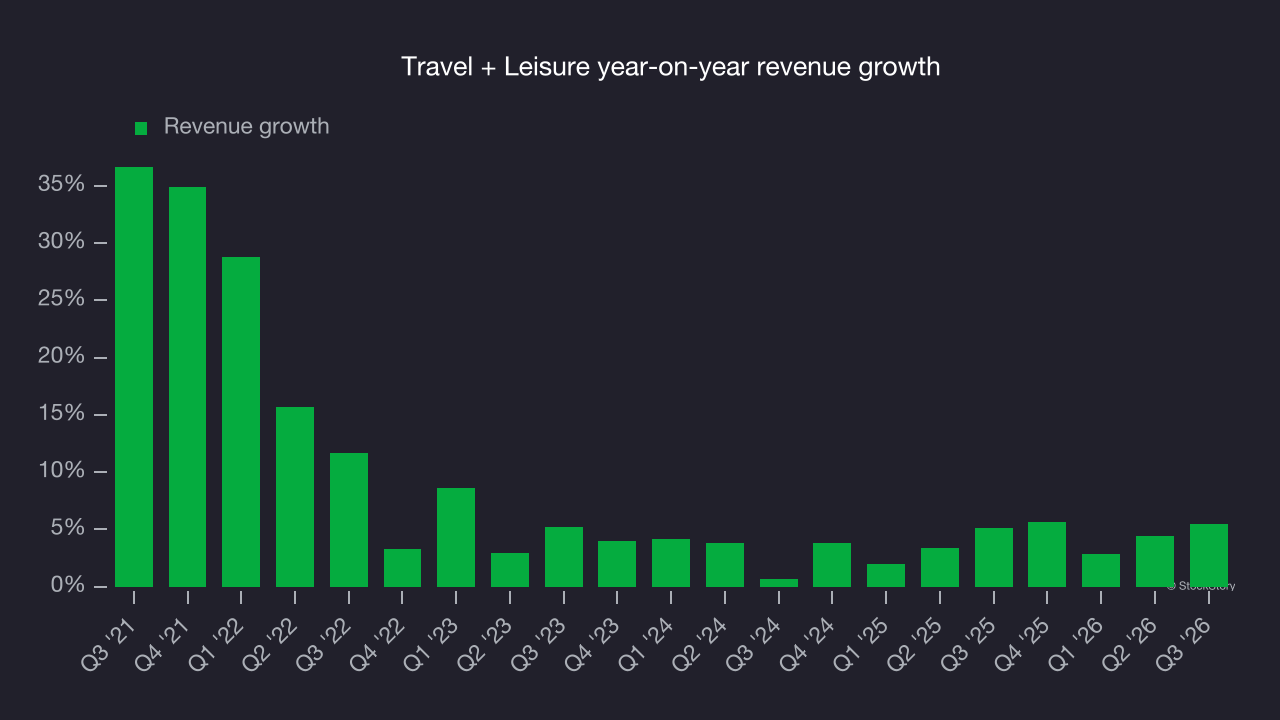
Travel + Leisure also discloses its number of tours conducted, which reached 213,000 in the latest quarter. Over the last two years, Travel + Leisure’s tours conducted averaged 3% year-on-year growth. This was in line with revenue growth during the same period, indicating that monetization stayed fairly consistent. 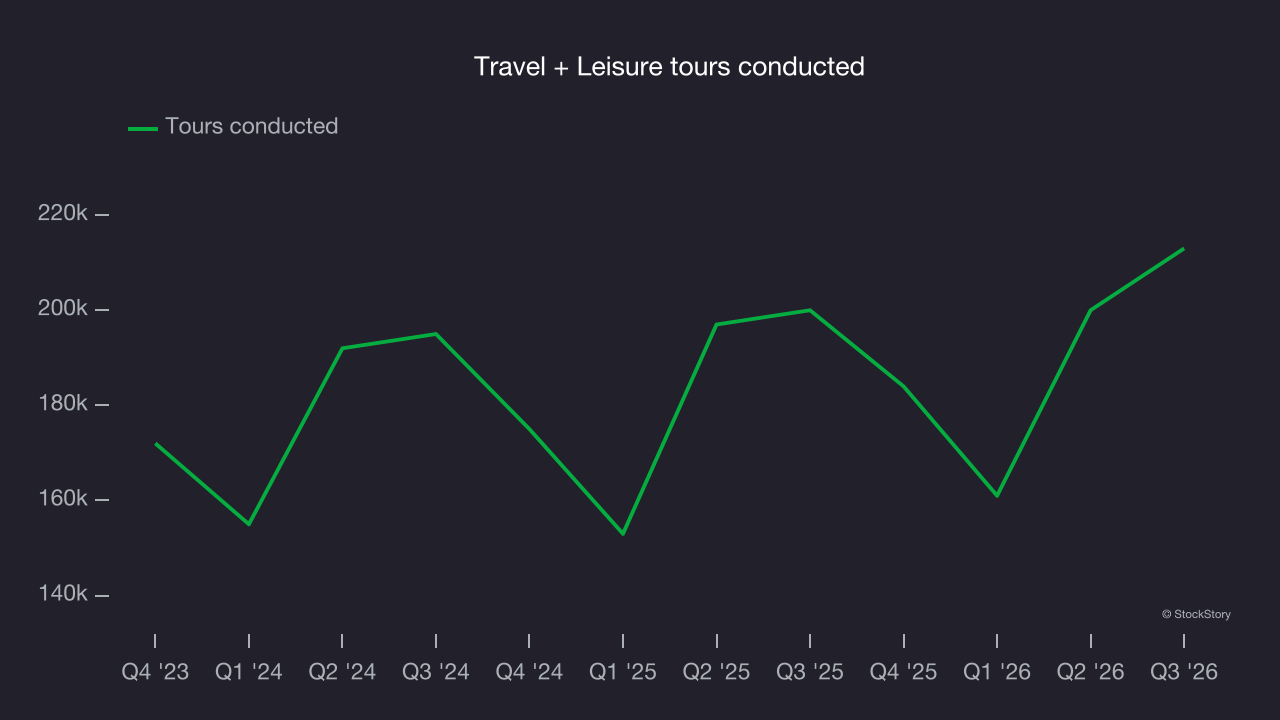
This quarter, Travel + Leisure reported year-on-year revenue growth of 5.5%, and its $1.10 billion of revenue exceeded Wall Street’s consensus estimates by 1%.
Looking ahead, sell-side analysts expect revenue to grow 4.6% over the next 12 months, according to S&P, similar to its two-year rate. This projection is underwhelming and suggests its newer products and services will not lead to better top-line performance yet.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Travel + Leisure’s operating margin has shrunk over the last 12 months and averaged 16.3% over the last two years. The company’s profitability was mediocre for a consumer discretionary business and shows it couldn’t pass its higher operating expenses onto its customers.
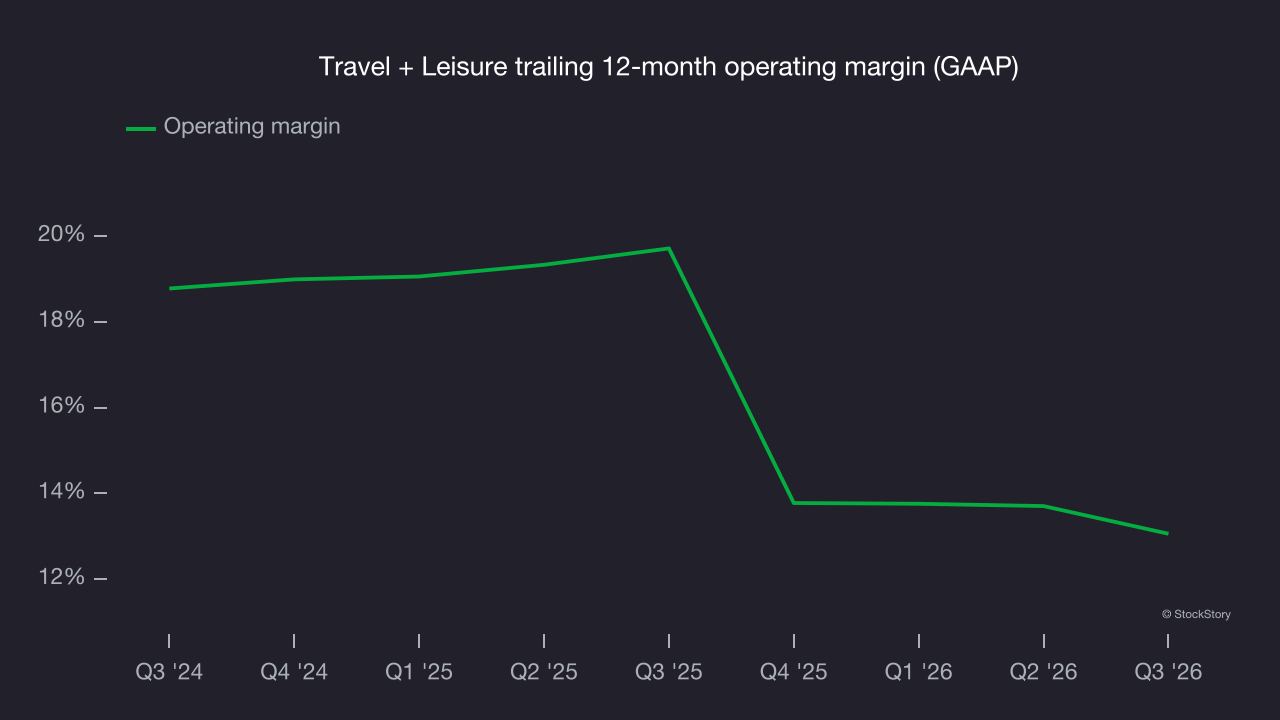
This quarter, Travel + Leisure generated an operating margin of 17.7%, down 2.8 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Travel + Leisure’s EPS grew at a 21.5% compounded annual growth rate over the last five years. This performance was better than its revenue growth but doesn’t tell us much about its business quality because its operating margin improvement lagged that of peers.
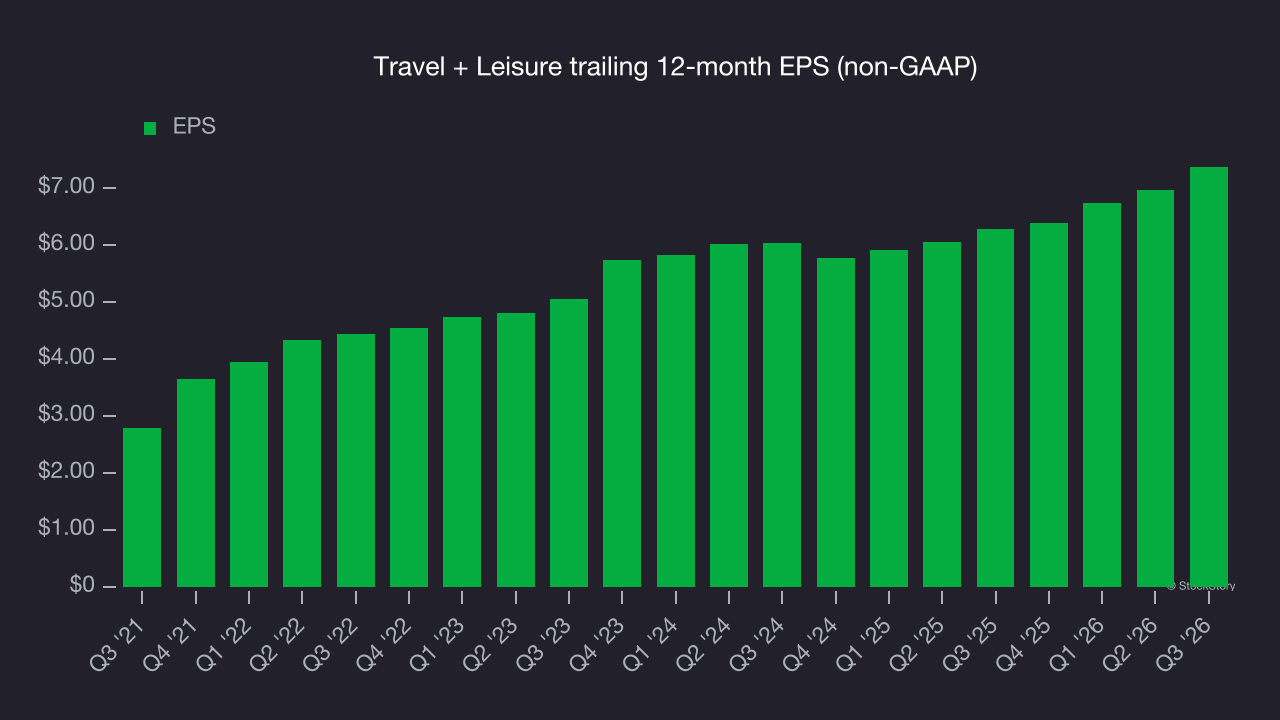
In Q3, Travel + Leisure reported adjusted EPS of $2.21, up from $1.80 in the same quarter last year. This result beat analysts’ consensus estimates by 7.5%. Over the next 12 months, Wall Street expects Travel + Leisure’s full-year EPS to grow 16.9% from $7.37 to $8.62, according to S&P.
Key takeaways from Travel + Leisure’s Q3 results
Travel + Leisure delivered a decent quarter, topping analysts’ consensus EPS estimates and narrowly beating Wall Street’s revenue expectations. Shares remained flat at $65.62 immediately after the results.
Travel + Leisure’s latest quarter is only one part of its longer-term business quality picture. Business quality, combined with valuation, can help determine whether the stock is a buy. For more on Travel + Leisure, read our full research report here (it’s free).