Although Fulton Financial (currently trading at $22.80 per share) has gained 9.8% over the last six months, it has trailed the S&P 500’s 16.8% return during that period. This might have investors contemplating their next move.
Is now the time to buy Fulton Financial, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is Fulton Financial Not Exciting?
We don’t have much confidence in Fulton Financial. Here are three reasons you should be careful with FULT, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
Two primary revenue streams drive bank earnings. While net interest income, which is earned by charging higher rates on loans than paid on deposits, forms the foundation, fee-based services across banking, credit, wealth management, and trading operations provide additional income.
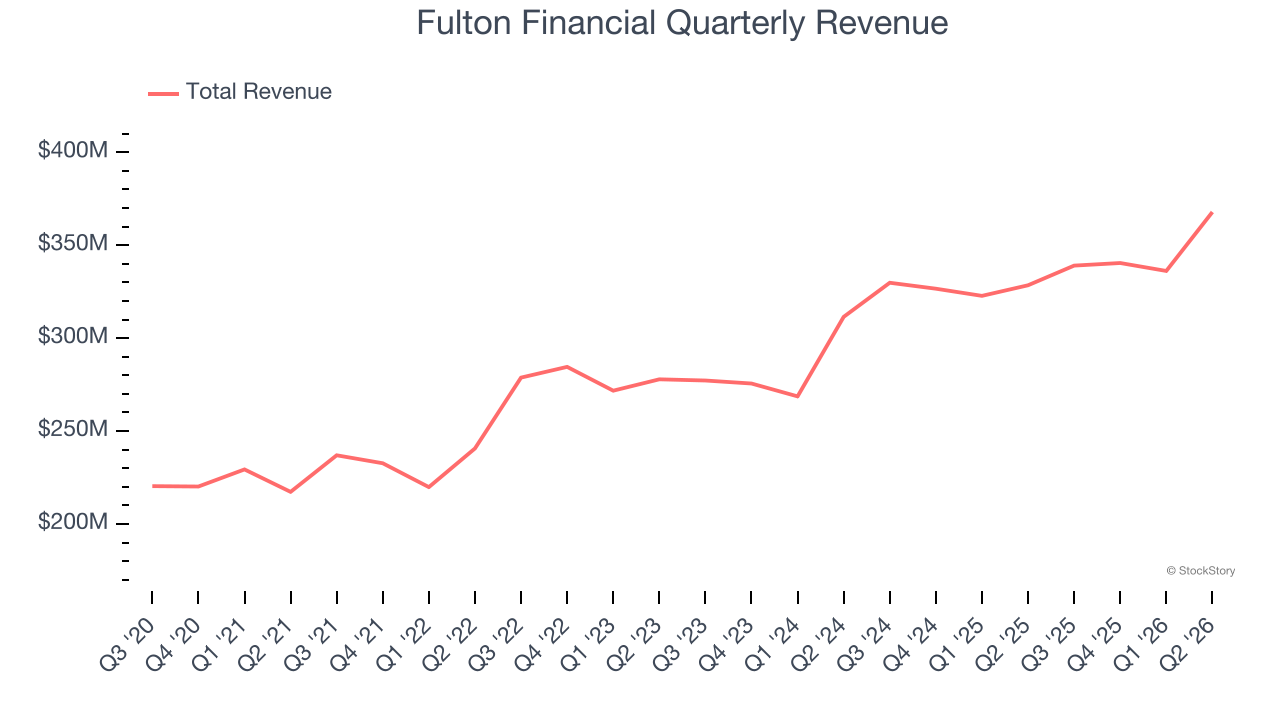
Over the last five years, Fulton Financial grew its revenue at a mediocre 9.3% compounded annual growth rate. This fell short of our benchmark for the banking sector.
2. EPS Barely Growing
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
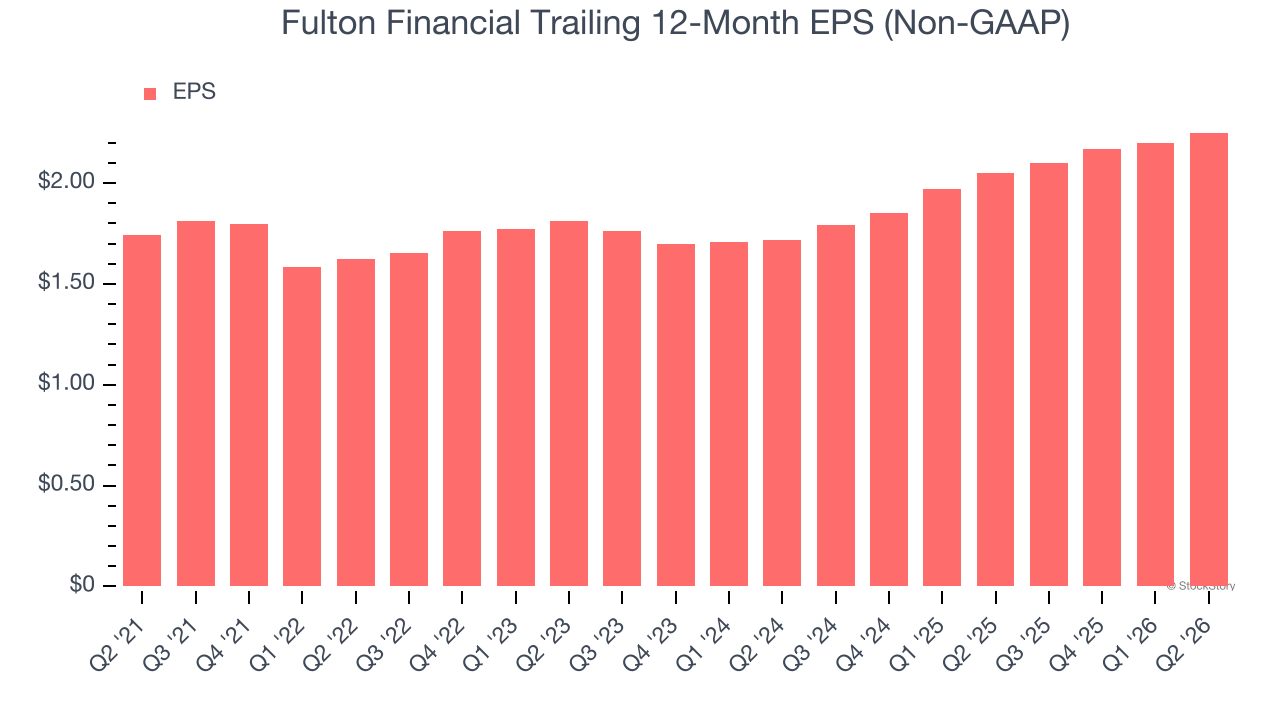
Fulton Financial’s EPS grew at a weak 5.2% compounded annual growth rate over the last five years, lower than its 9.3% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
3. Projected TBVPS Growth Is Slim
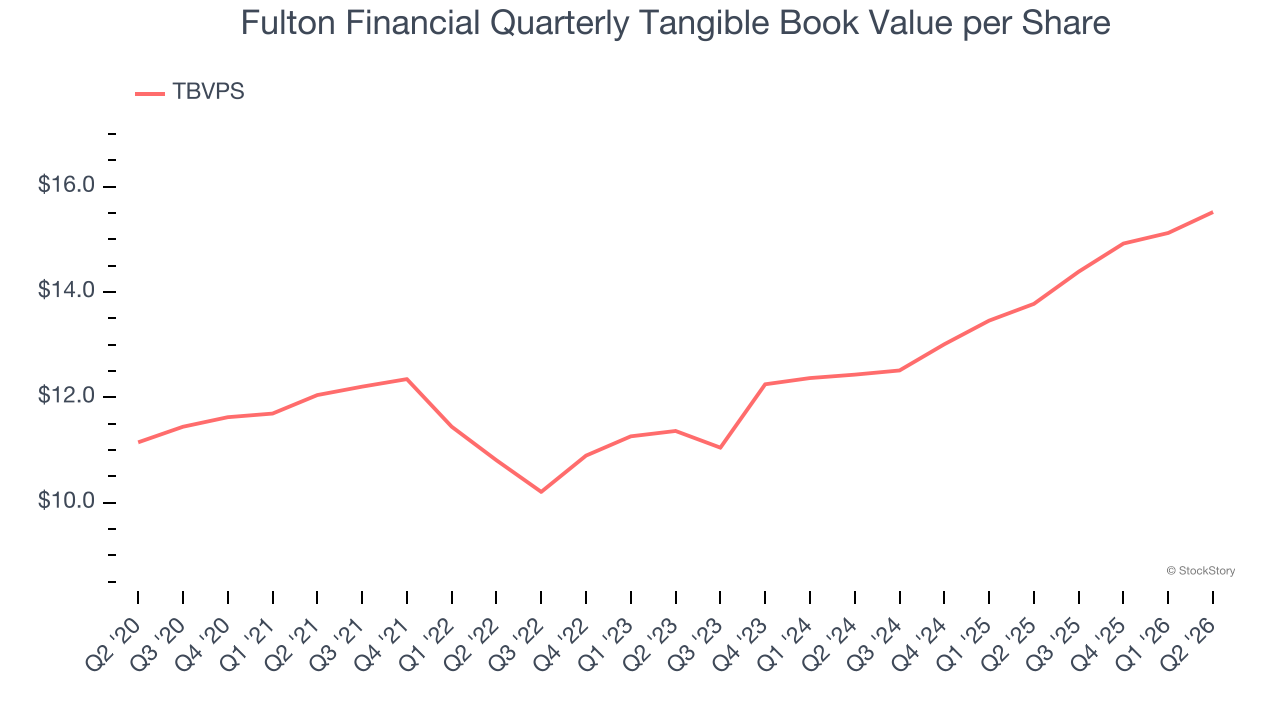
Tangible book value per share (TBVPS) growth is driven by a bank’s ability to earn more than its cost of capital through lending activities while maintaining a strong balance sheet.
Over the next 12 months, Consensus estimates call for Fulton Financial’s TBVPS to grow by 9.8% to $17.04, paltry growth rate.
Final Judgment
Fulton Financial’s business quality ultimately falls short of our standards. With its shares trailing the market in recent months, the stock trades at 1.2× forward P/B (or $22.80 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re fairly confident there are better stocks to buy right now. We’d suggest looking at a dominant aerospace business that has perfected its M&A strategy.
Stocks We Would Buy Instead of Fulton Financial
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.