Sonos’s 33.4% return over the past six months has outpaced the S&P 500 by 16.6%, and its stock price has climbed to $18.13 per share. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now the time to buy Sonos, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think Sonos Will Underperform?
We’re happy investors have made money, but we’re passing on Sonos for now. Here are three reasons we avoid SONO, plus one stock we’d rather own.
1. Revenue Spiraling Downwards
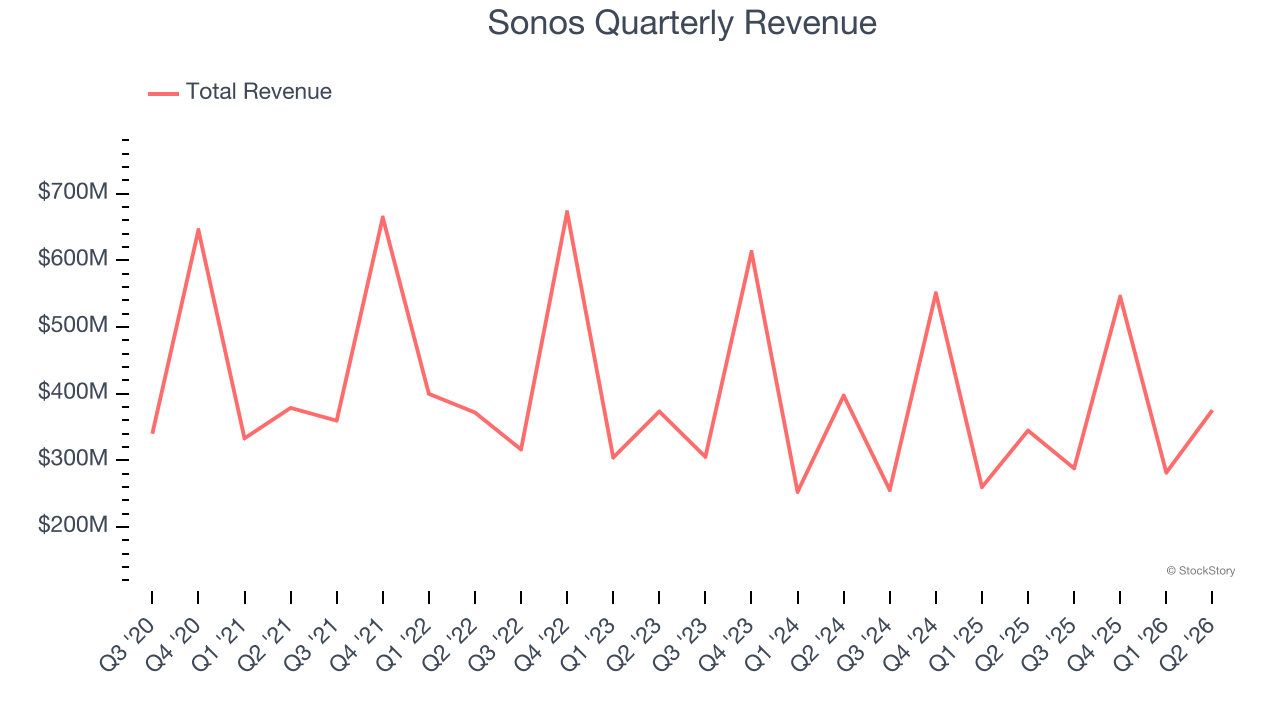
Examining a company’s long-term performance can provide clues about its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Sonos struggled to consistently generate demand over the last five years as its sales dropped at a 2.6% annual rate. This wasn’t a great result and is a sign of poor business quality.
2. EPS Trending Down
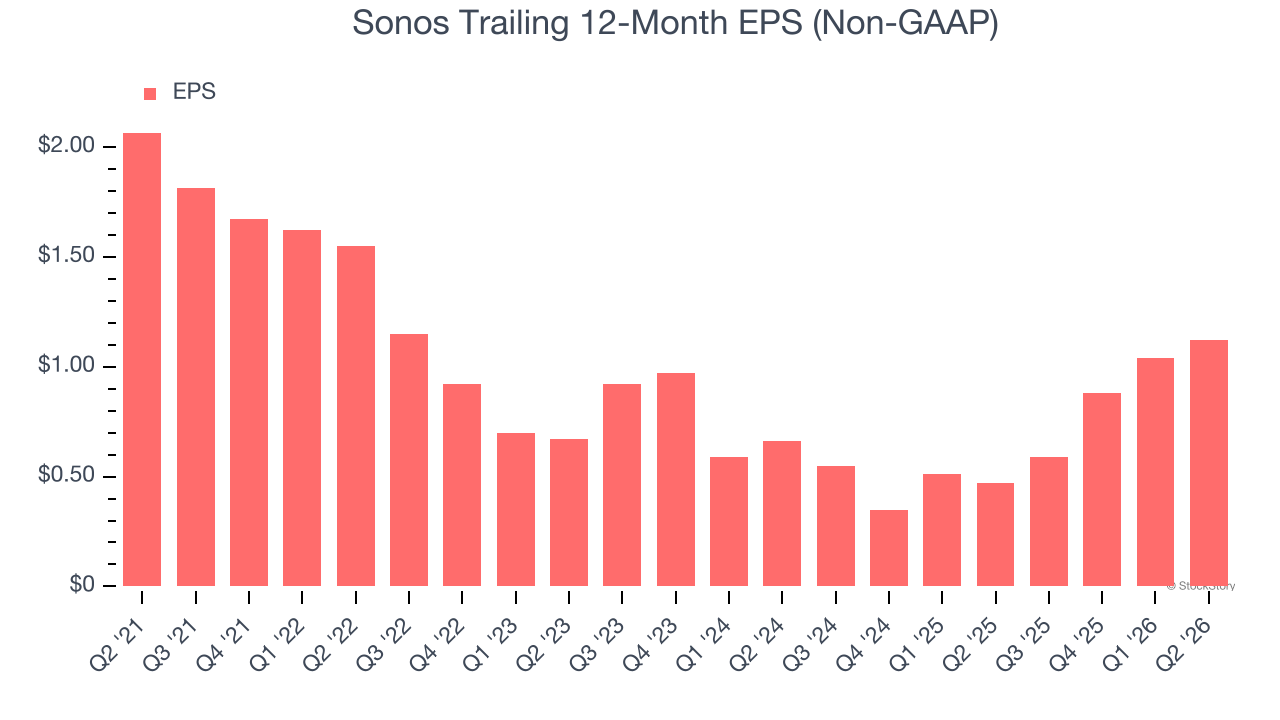
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Sadly for Sonos, its EPS declined by 11.5% annually over the last five years, more than its revenue. This tells us the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
3. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
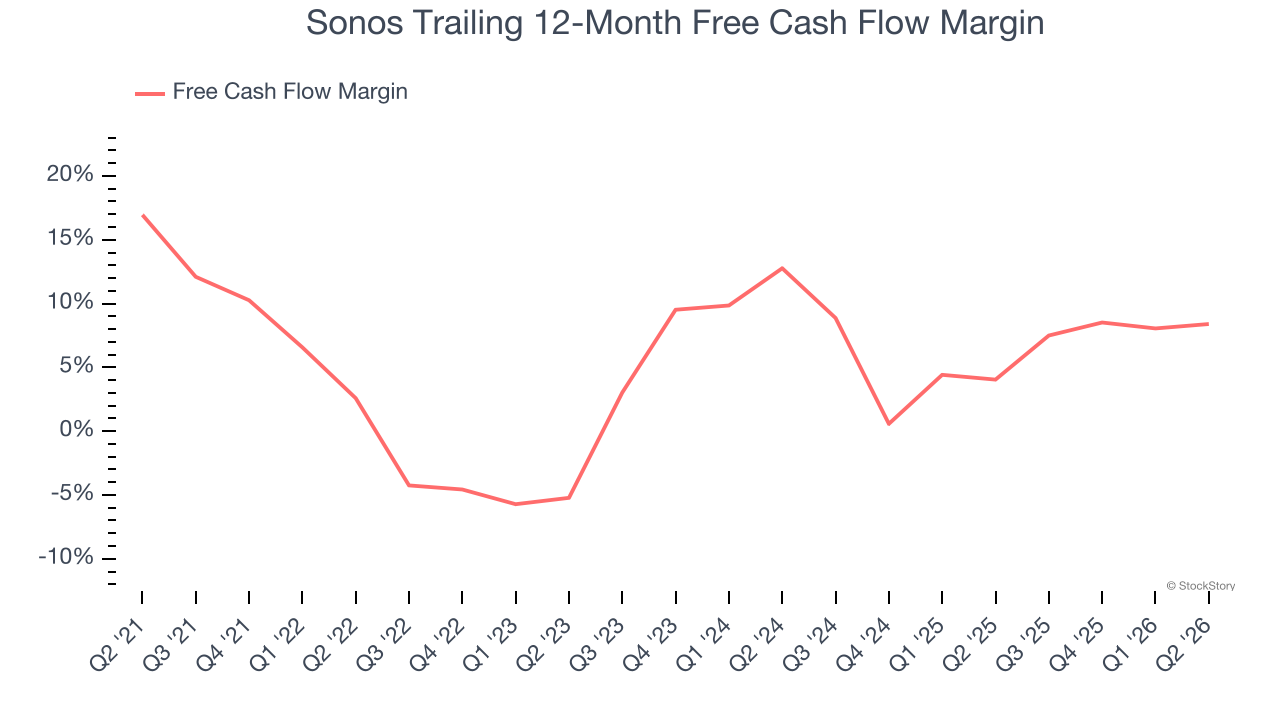
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Sonos has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 6.3%, below what we’d expect for a consumer discretionary business.
Final Judgment
We see the value of companies helping consumers, but in the case of Sonos, we’re out. With its shares topping the market in recent months, the stock trades at 19.5× forward P/E (or $18.13 per share). This multiple tells us a lot of good news is priced in - we think other companies feature superior fundamentals at the moment. Let us point you toward our favorite semiconductor picks and shovels play.
Stocks We Like More Than Sonos
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.