Even though Cars.com (currently trading at $9.71 per share) has gained 8.9% over the last six months, it has lagged the S&P 500’s 16.8% return during that period. This might have investors contemplating their next move.
Is there a buying opportunity in Cars.com, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Cars.com Not Exciting?
We’re sitting this one out for now. Here are three reasons why there are better opportunities than CARS, plus one stock we’d rather own.
1. Dealer Customers Hit a Plateau
As an online marketplace, Cars.com generates revenue growth by increasing both the number of users on its platform and the average order size in dollars.
Cars.com struggled with new customer acquisition over the last two years as its dealer customers were flat at 19,343. This performance isn’t ideal because internet usage is secular, meaning there are typically unaddressed market opportunities. If Cars.com wants to accelerate growth, it likely needs to enhance the appeal of its current offerings or innovate with new products. 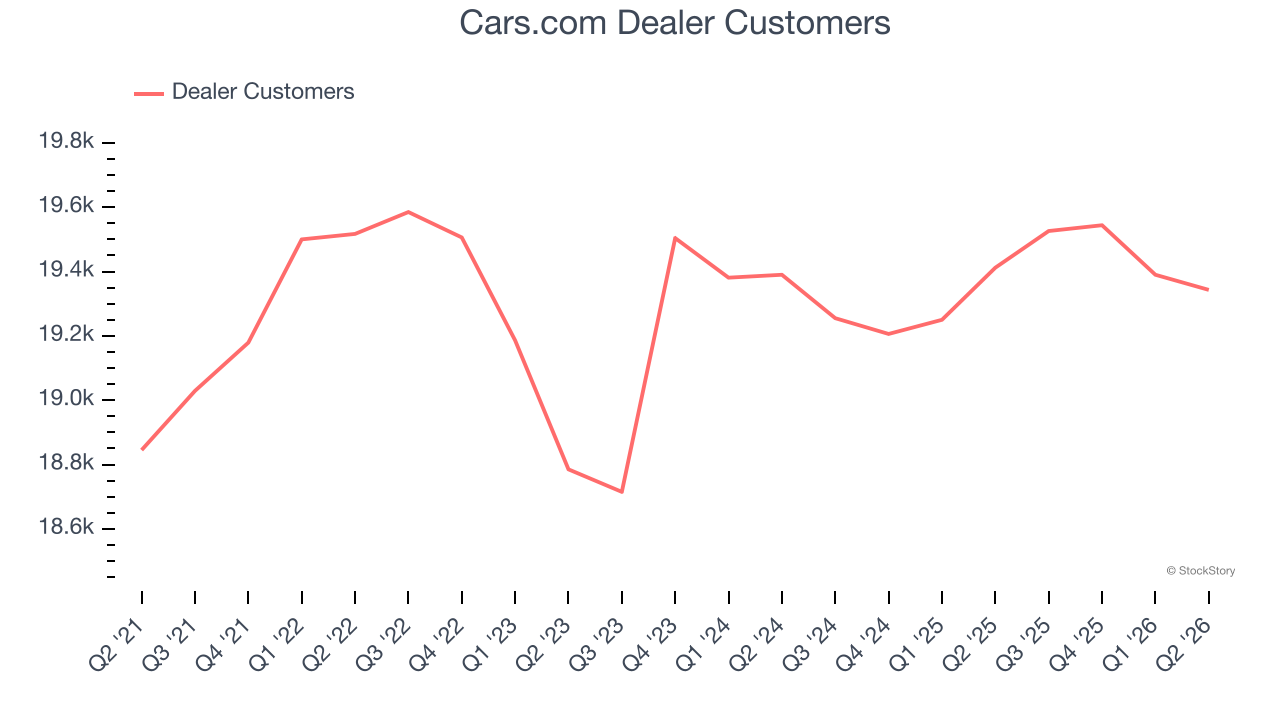
2. Customer Spending Stalls, Engagement Falling?
Average revenue per buyer (ARPB) is a critical metric to track because it measures how much the company earns in transaction fees from each buyer. ARPB also gives us unique insights into a user’s average order size and Cars.com’s take rate, or “cut”, on each order.
Cars.com’s ARPB has been roughly flat over the last two years. This raises questions about its platform’s health when paired with its inability to grow dealer customers. If Cars.com wants to increase its buyers, it must either develop new features or provide some existing ones for free. 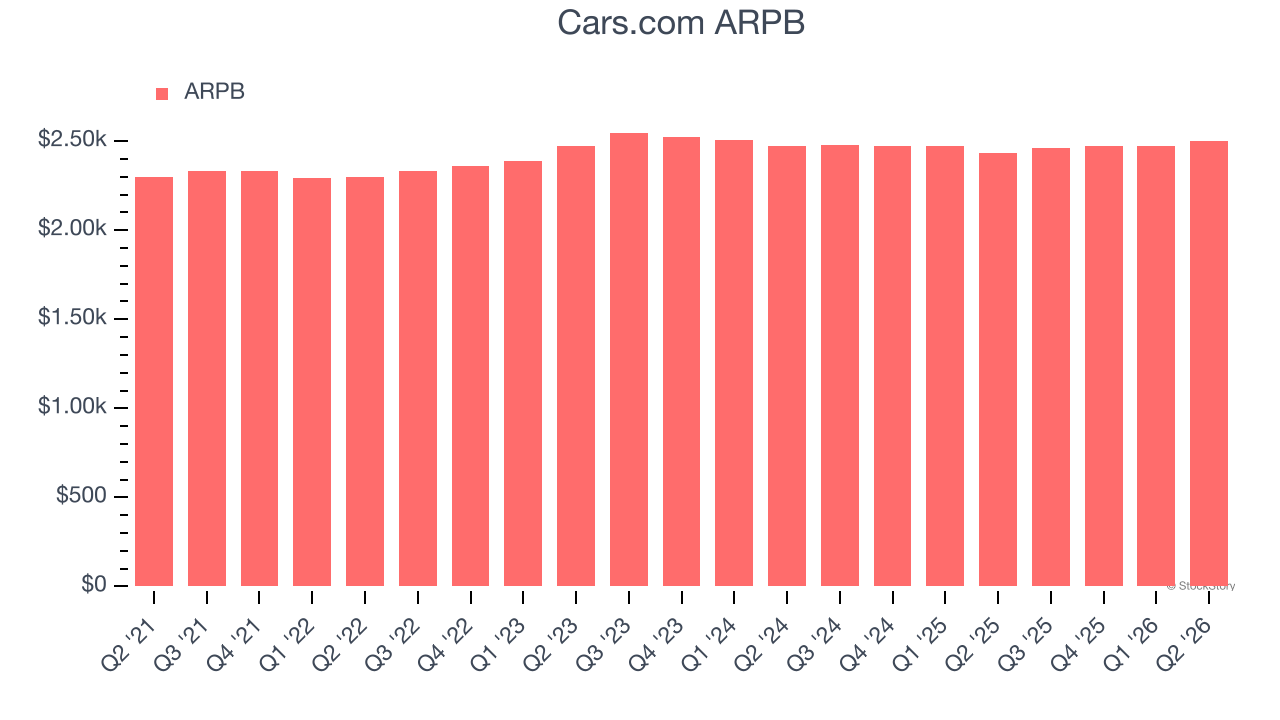
3. EPS Trending Down
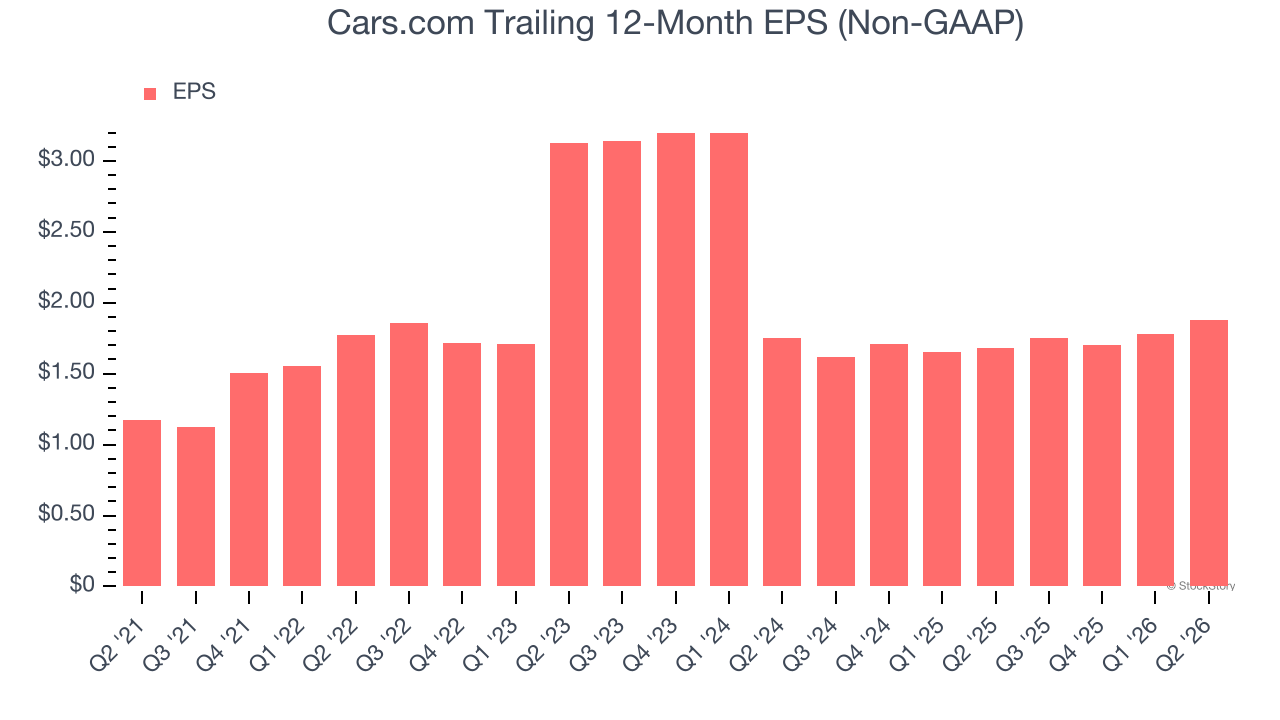
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for Cars.com, its EPS declined by 15.6% annually over the last three years while its revenue grew by 2.8%. This tells us the company became less profitable on a per-share basis as it expanded.
Final Judgment
Cars.com isn’t a terrible business, but it doesn’t pass our quality test. With its shares trailing the market in recent months, the stock trades at 4.5× forward EV/EBITDA (or $9.71 per share). While this valuation is optically cheap, the potential downside is big given its shaky fundamentals. We’re pretty confident there are superior stocks to buy right now. Let us point you toward the most dominant software business in the world.
Stocks We Would Buy Instead of Cars.com
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.