While the S&P 500 is up 16.8% since April 2026, Talos Energy (currently trading at $17.07 per share) has lagged behind, posting a return of 7.3%. This might have investors contemplating their next move.
Given the relatively weaker price action, is now a good time to buy TALO, or is it a pass? Find out in our full research report, it’s free.
Why Are We Positive on TALO?
Operating its own deepwater production facilities with names like Tarantula, Pompano, and Brutus, Talos Energy (NYSE: TALO) explores for and produces oil and natural gas from offshore wells in the Gulf of Mexico and offshore Mexico.
1. Skyrocketing Revenue Shows Strong Momentum
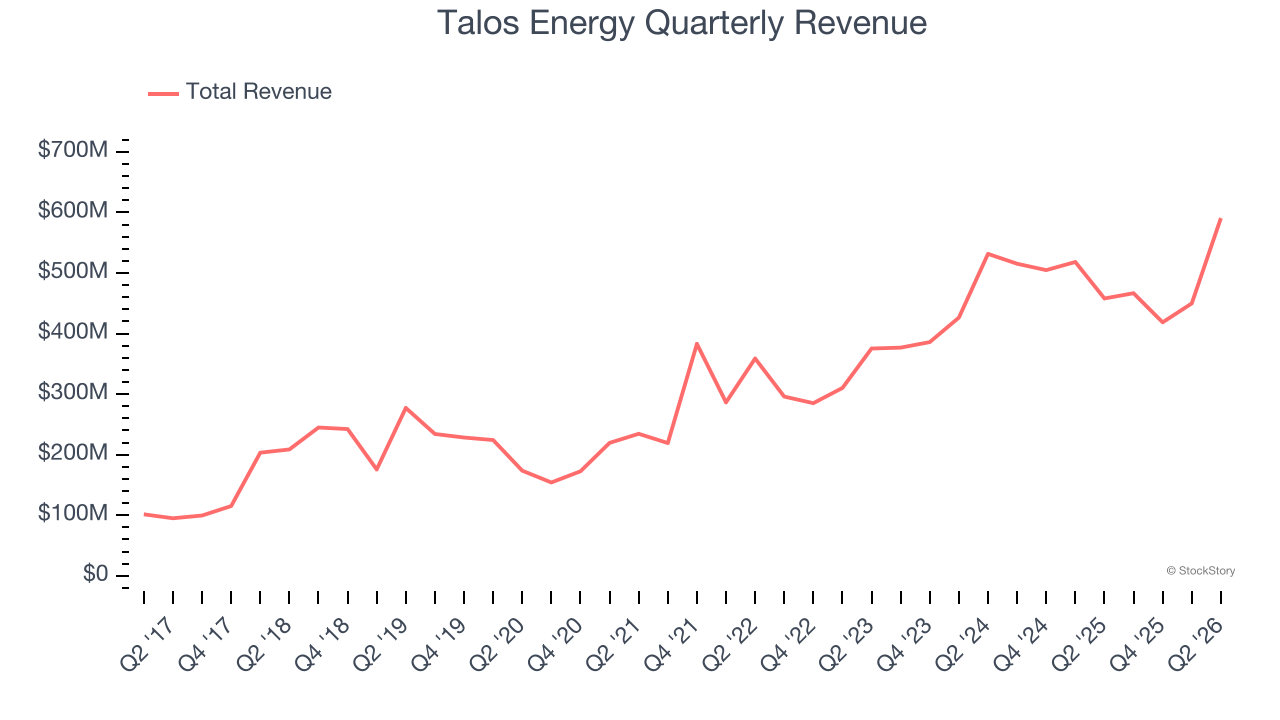
A company’s long-term performance can give signals about its business quality. Even a bad business, especially in a cyclical industry, can shine for a year or so, but a top-tier one should exhibit resilience through cycles. Thankfully, Talos Energy’s 19.8% annualized revenue growth over the last five years was excellent. Its growth surpassed the average energy upstream and integrated energy company and shows its offerings resonate with customers.
2. Elite Gross Margin Powers Best-In-Class Business Model
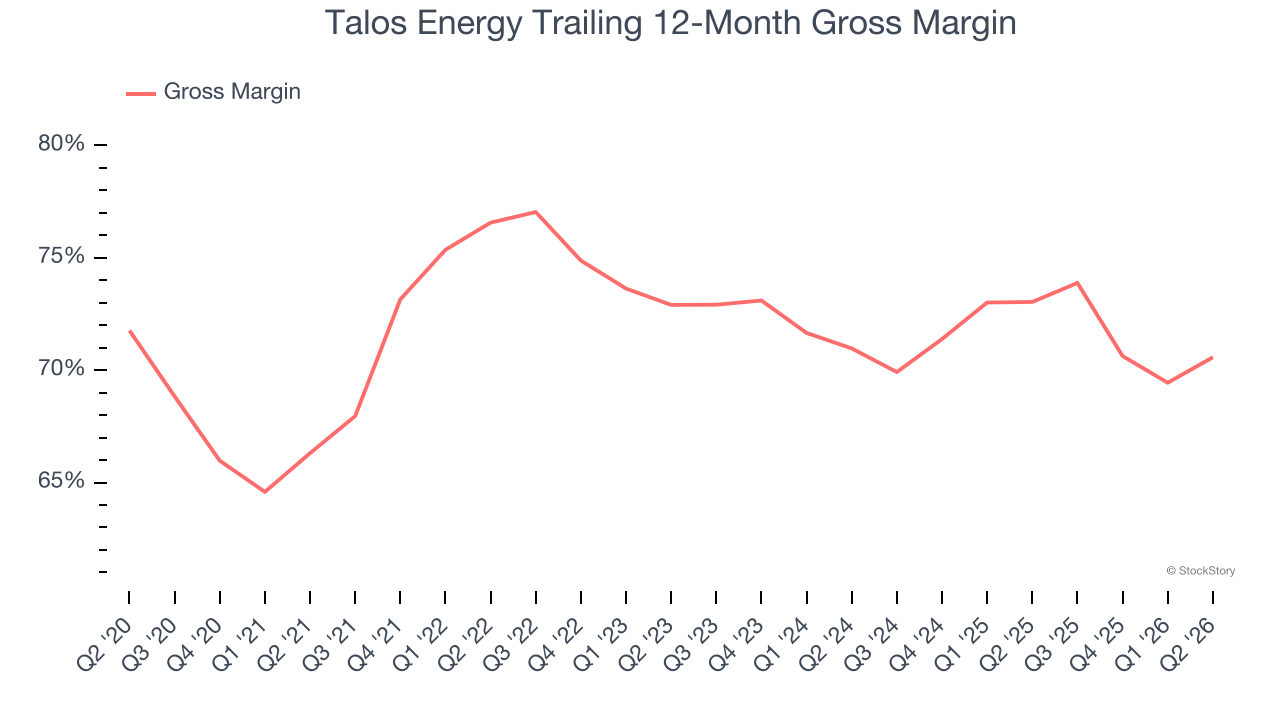
In a single quarter or year, gross margins in the sector can swing wildly due to commodity prices, hedging, or changes in labor costs. Over a multi-year period across different points in the cycle, gross margin differences can signal whether a company is a structurally-advantaged producer (“rock” quality, takeaway, operating costs) or not.
Talos Energy, which averaged 72.5% gross margin over the last five years, exhibits enviable unit economics in the sector. It means the company will remain profitable at lower commodity prices than peers with inferior gross margins and serves as an advantaged starting point for ultimate operating profits and free cash flow generation.
3. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
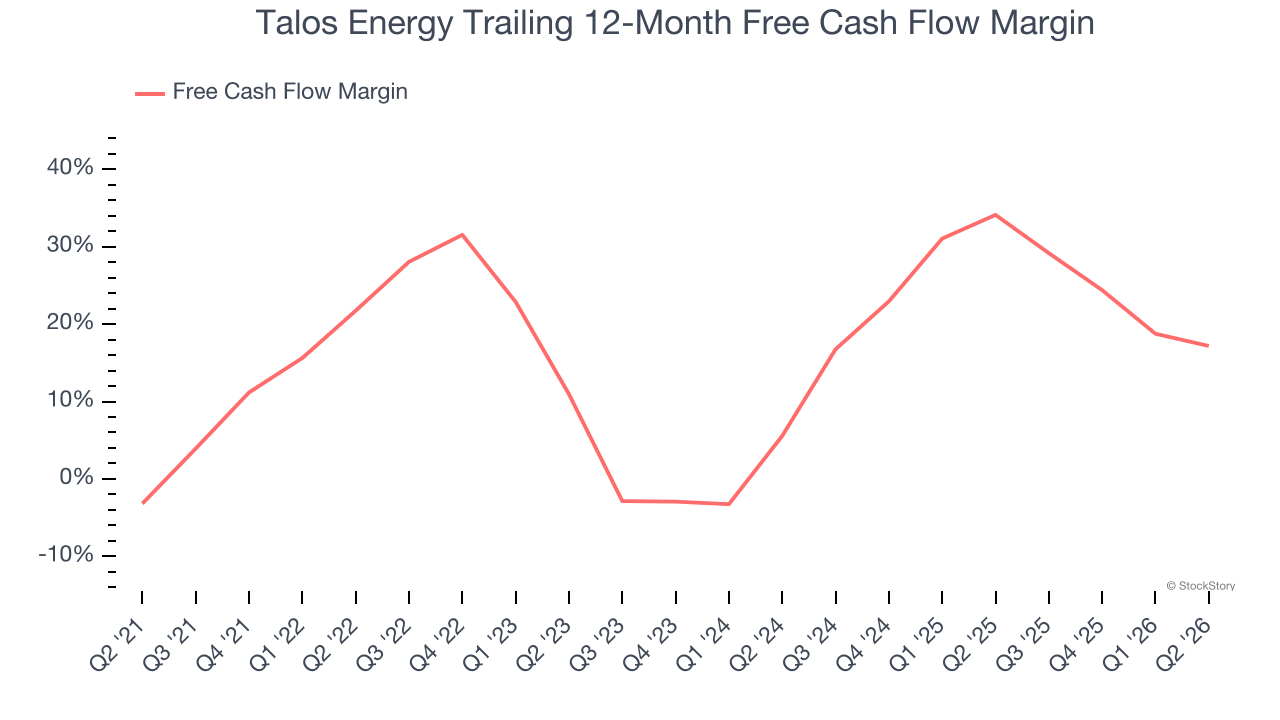
Talos Energy has shown terrific cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors, and stay ahead of the competition. The company’s free cash flow margin was among the best in the energy upstream and integrated energy sector, averaging 18.6% over the last five years.
Final Judgment
These are just a few reasons why Talos Energy ranks highly on our list. With its shares lagging the market recently, the stock trades at 9.9× forward P/E (or $17.07 per share). Is now the time to initiate a position? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than Talos Energy
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.