Over the past six months, ICF International has been a great trade, beating the S&P 500 by 16.2%. Its stock price has climbed to $88.80, representing a healthy 29.9% increase. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is there a buying opportunity in ICF International, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Do We Think ICF International Will Underperform?
We’re happy investors have made money, but we don’t have much confidence in ICF International. Here are three reasons you should be careful with ICFI, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
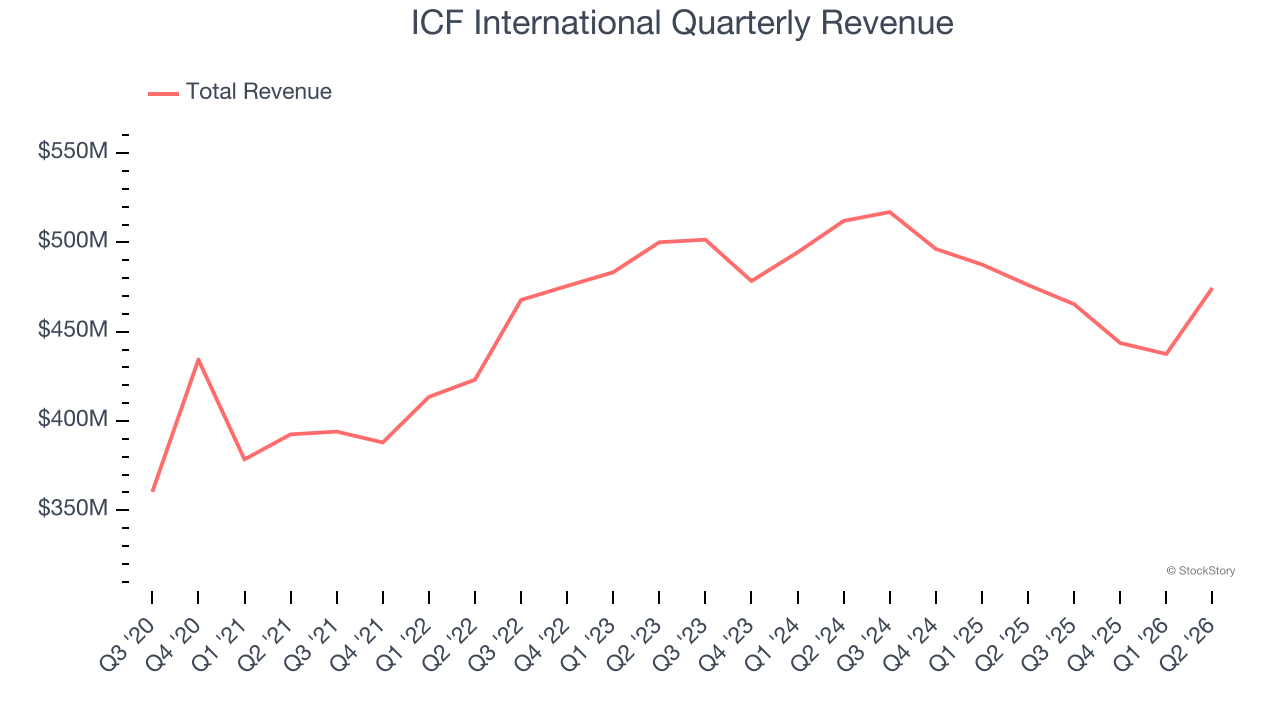
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Regrettably, ICF International’s sales grew at a tepid 3.1% compounded annual growth rate over the last five years. This fell short of our benchmark for the business services sector.
2. Backlog Declines as Orders Drop
In addition to reported revenue, backlog is a useful data point for analyzing Government & Technical Consulting companies. This metric shows the value of outstanding orders that have not yet been executed or delivered, giving visibility into ICF International’s future revenue streams.
ICF International’s backlog came in at $3.3 billion in the latest quarter, and it averaged 5.7% year-on-year declines over the last two years. This performance was underwhelming and shows the company is not winning new orders. It also suggests there may be increasing competition or market saturation. 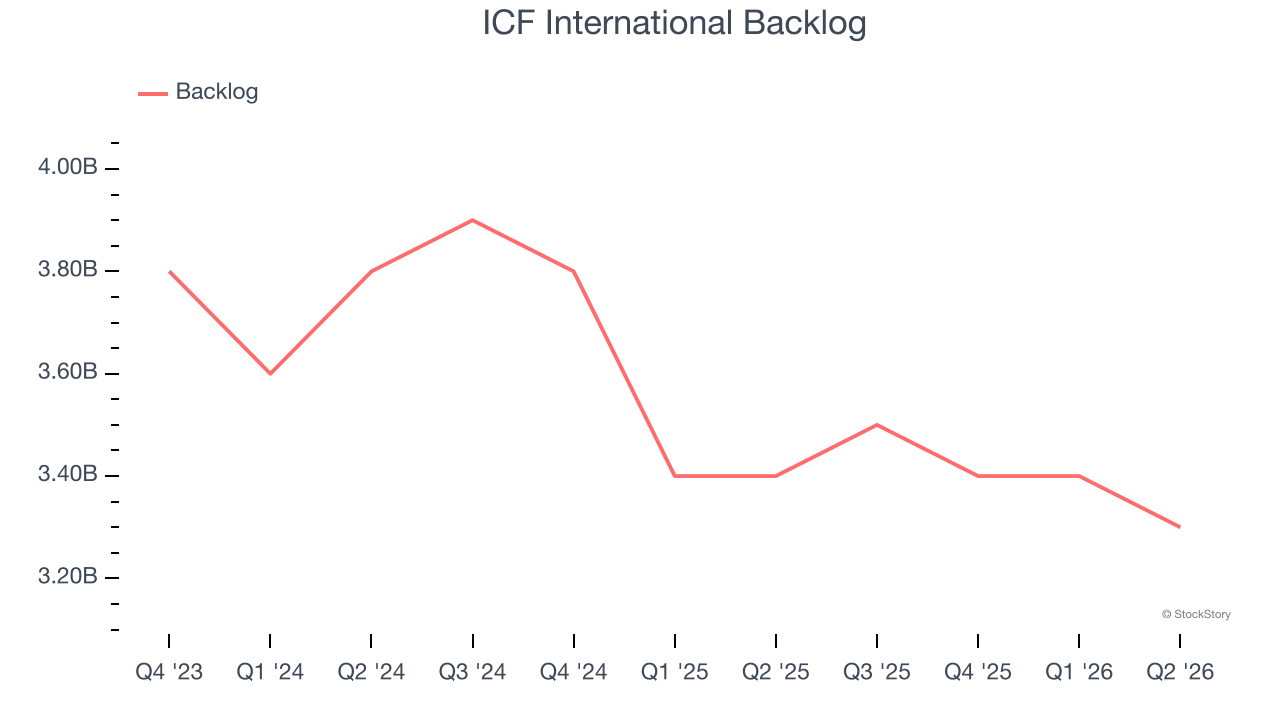
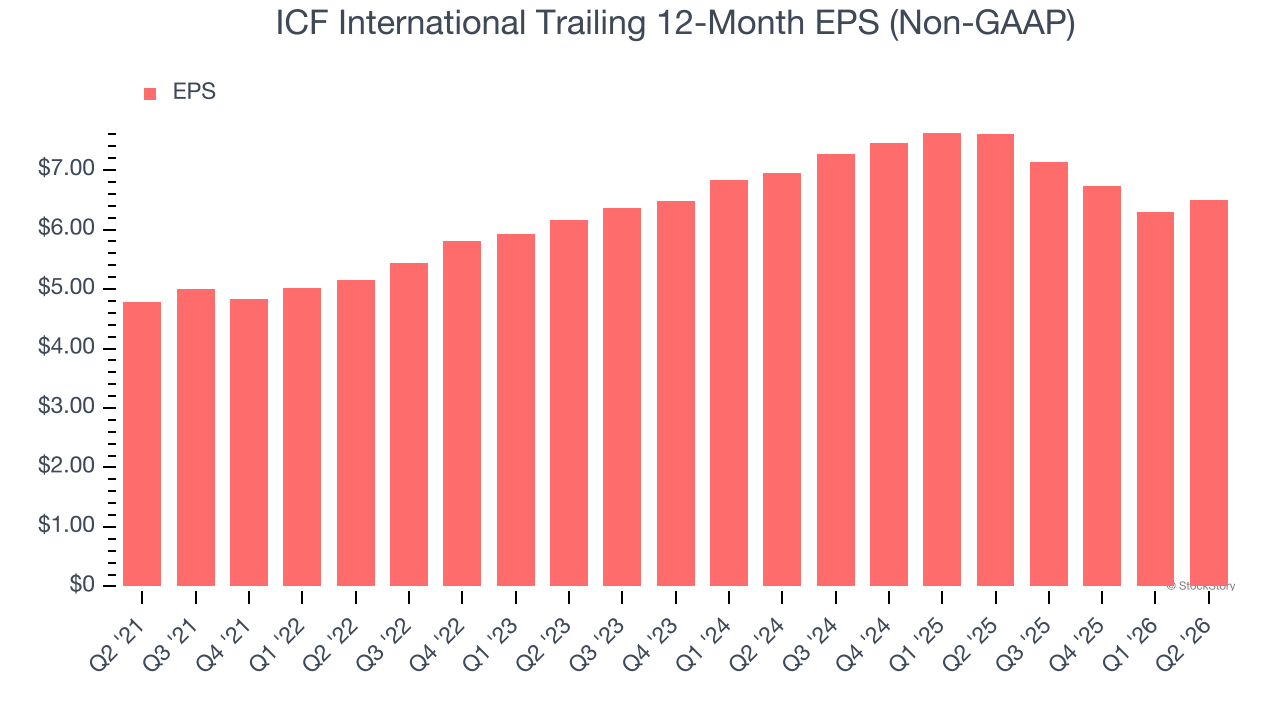
3. EPS Barely Growing
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
ICF International’s EPS grew at 6.3% compounded annual growth rate over the last five years. On the bright side, this performance was better than its 3.1% annualized revenue growth and tells us the company became more profitable on a per-share basis as it expanded.
Final Judgment
We cheer for all companies making their customers lives easier, but in the case of ICF International, we’ll be cheering from the sidelines. With its shares outperforming the market lately, the stock trades at 11.9× forward P/E (or $88.80 per share). This valuation tells us a lot of optimism is priced in - you can find more timely opportunities elsewhere. Let us point you toward an all-weather company that owns household favorite Taco Bell.
Stocks We Would Buy Instead of ICF International
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.