Over the past six months, LGI Homes has been a great trade, beating the S&P 500 by 8%. Its stock price has climbed to $50.78, representing a healthy 21.7% increase. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy LGI Homes, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think LGI Homes Will Underperform?
Despite the momentum, we’re passing on LGI Homes for now. Here are three reasons why there are better opportunities than LGIH, plus one stock we’d rather own.
1. Revenue Spiraling Downwards
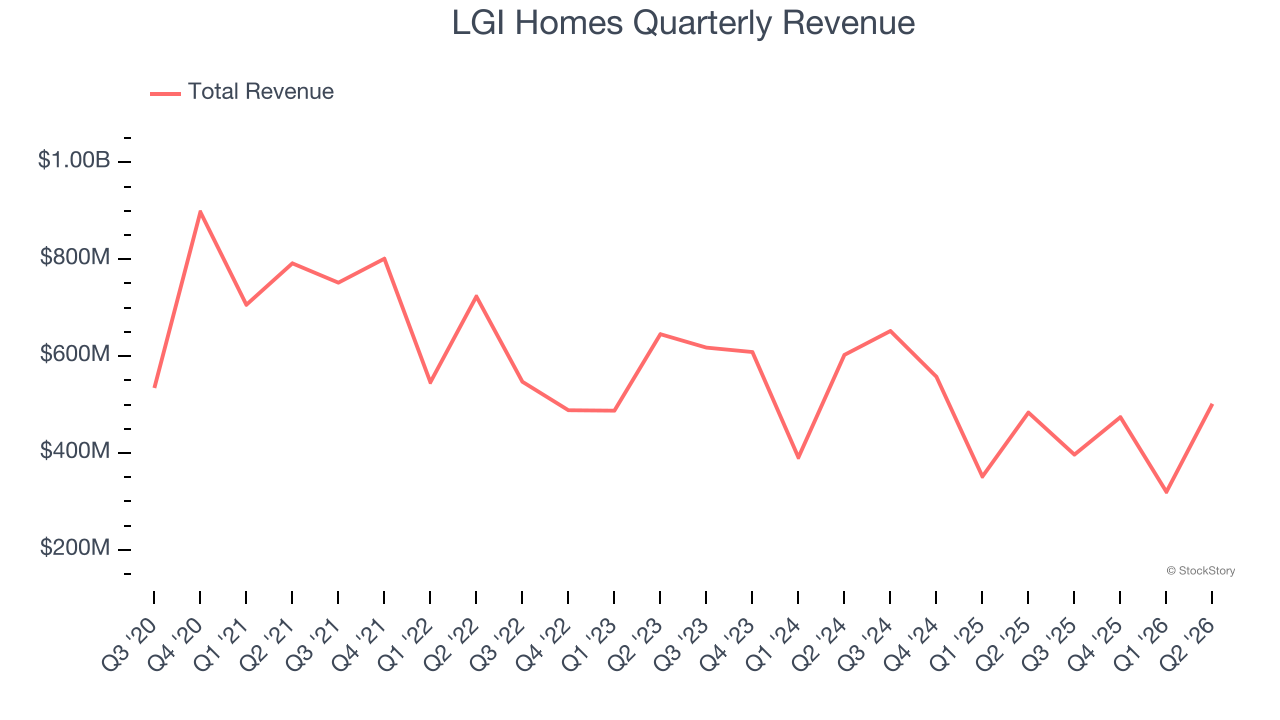
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Over the last five years, LGI Homes’s demand was weak and its revenue declined by 10.4% per year. This wasn’t a great result and is a sign of poor business quality.
2. New Investments Fail to Bear Fruit as ROIC Declines
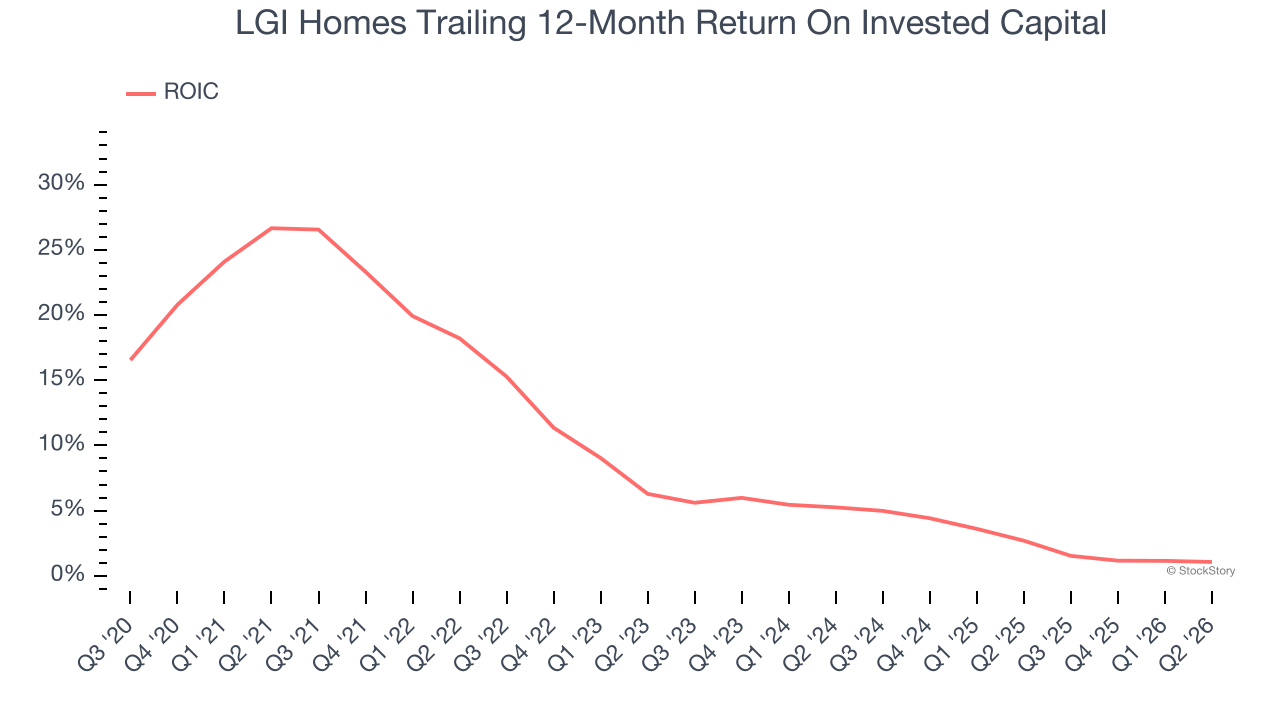
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Unfortunately, LGI Homes’s ROIC has decreased significantly over the last few years. Paired with its already low returns, these declines suggest its profitable growth opportunities are few and far between.
3. High Debt Levels Increase Risk
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
LGI Homes’s $1.58 billion of debt exceeds the $61.08 million of cash on its balance sheet. Furthermore, its 21× net-debt-to-EBITDA ratio (based on its EBITDA of $73.36 million over the last 12 months) shows the company is overleveraged.
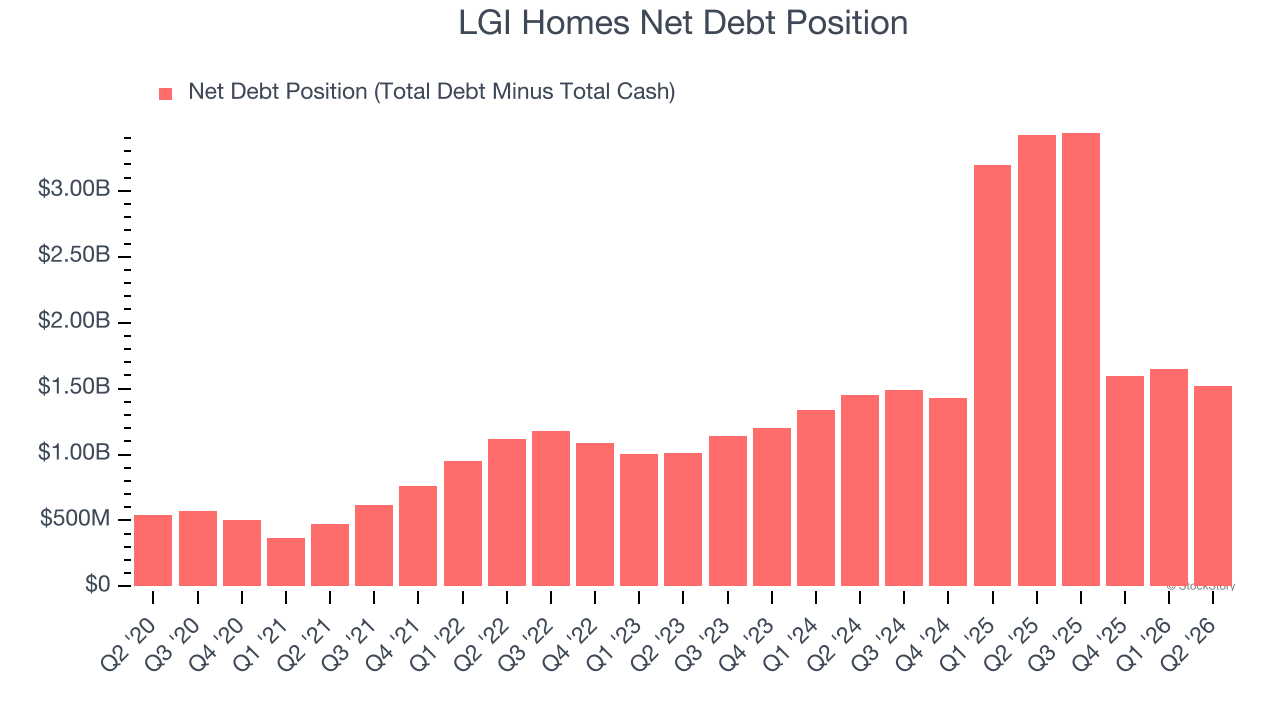
At this level of debt, incremental borrowing becomes increasingly expensive and credit agencies could downgrade the company’s rating if profitability falls. LGI Homes could also be backed into a corner if the market turns unexpectedly – a situation we seek to avoid as investors in high-quality companies.
We hope LGI Homes can improve its balance sheet and remain cautious until it increases its profitability or pays down its debt.
Final Judgment
We see the value of companies helping their customers, but in the case of LGI Homes, we’re out. With its shares beating the market recently, the stock trades at 16.8× forward P/E (or $50.78 per share). At this valuation, there’s a lot of good news priced in - we think there are better stocks to buy right now. Let us point you toward one of our all-time favorite software stocks.
Stocks We Would Buy Instead of LGI Homes
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.