Even though Wendy's (currently trading at $7.49 per share) has gained 6.3% over the last six months, it has lagged the S&P 500’s 13.7% return during that period. This might have investors contemplating their next move.
Is now the time to buy Wendy's, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Do We Think Wendy's Will Underperform?
We’re passing on Wendy's for now. Here are three reasons we avoid WEN, plus one stock we’d rather own.
1. Shrinking Same-Store Sales Indicate Waning Demand
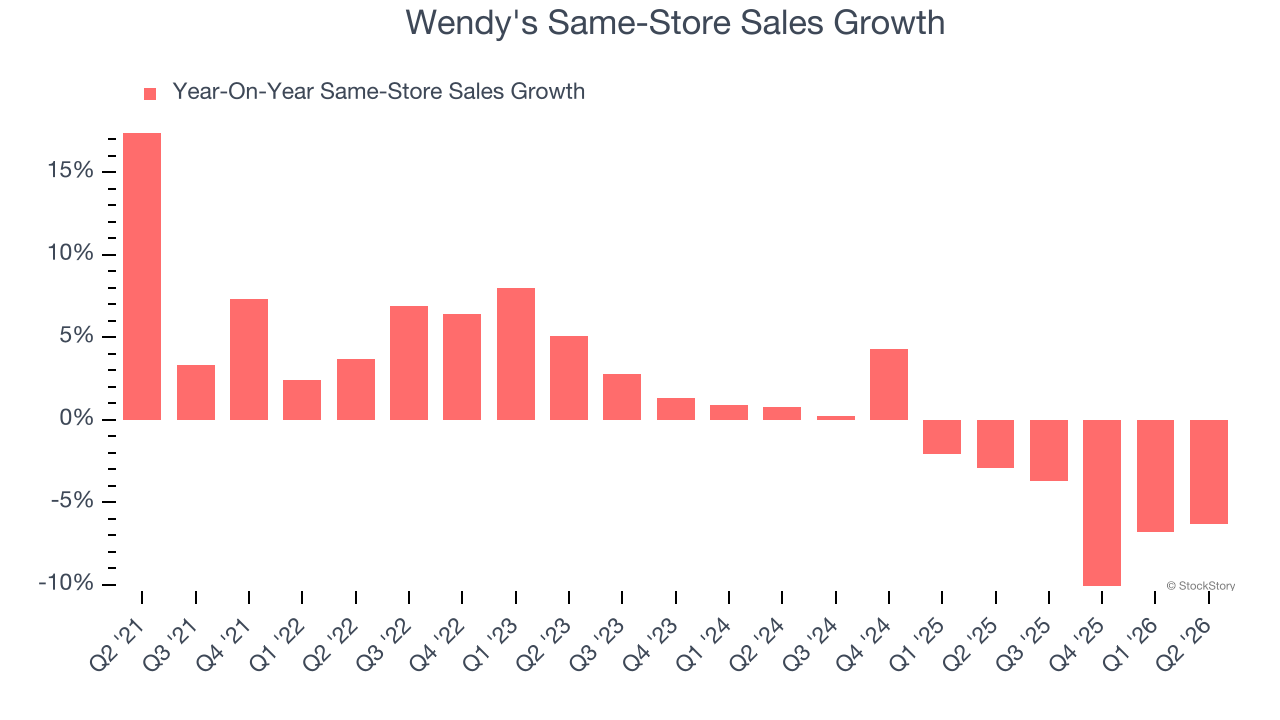
Same-store sales is an industry measure of whether revenue is growing at existing restaurants, and it is driven by customer visits (often called traffic) and the average spending per customer (ticket).
Wendy’s demand has been shrinking over the last two years as its same-store sales have averaged 3.4% annual declines.
2. Shrinking Operating Margin
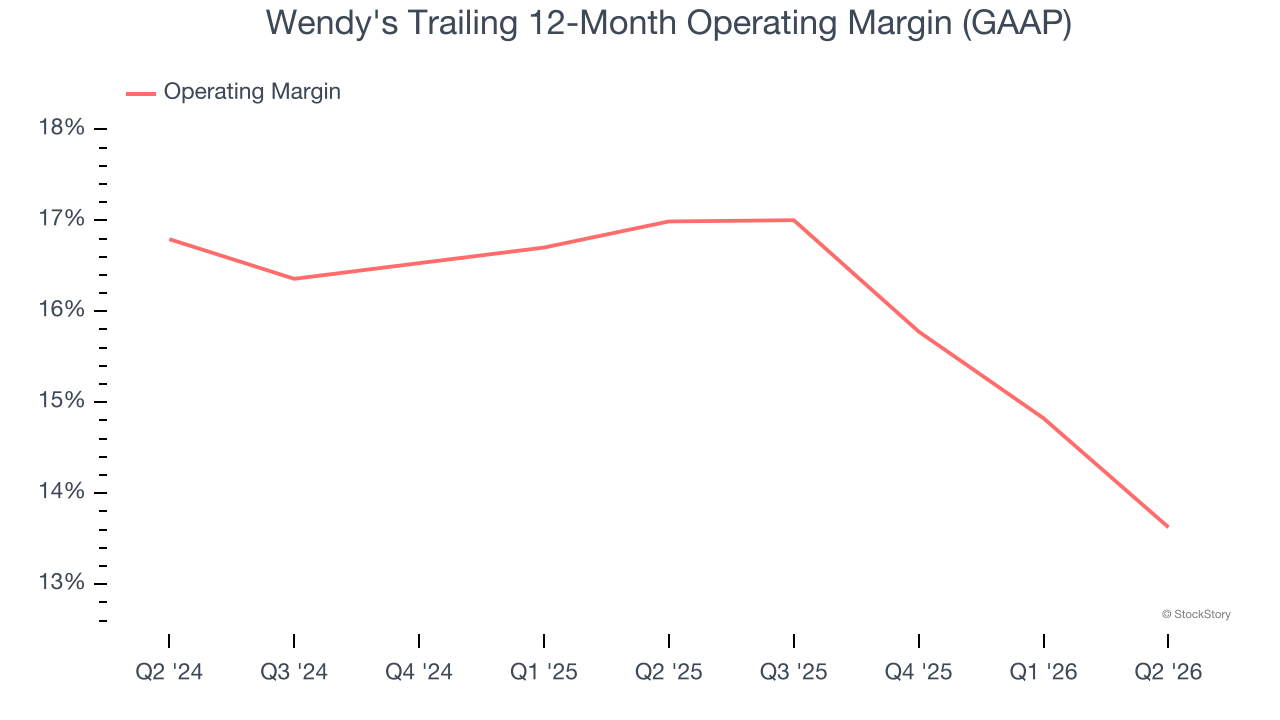
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Analyzing the trend in its profitability, Wendy’s operating margin decreased by 3.4 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its operating margin for the trailing 12 months was 13.6%.
3. High Debt Levels Increase Risk
Debt is a tool that can boost company returns but presents risks if used irresponsibly. As long-term investors, we aim to avoid companies taking excessive advantage of this instrument because it could lead to insolvency.
Wendy’s $4.07 billion of debt exceeds the $341.2 million of cash on its balance sheet. Furthermore, its 8× net-debt-to-EBITDA ratio (based on its EBITDA of $486.7 million over the last 12 months) shows the company is overleveraged.
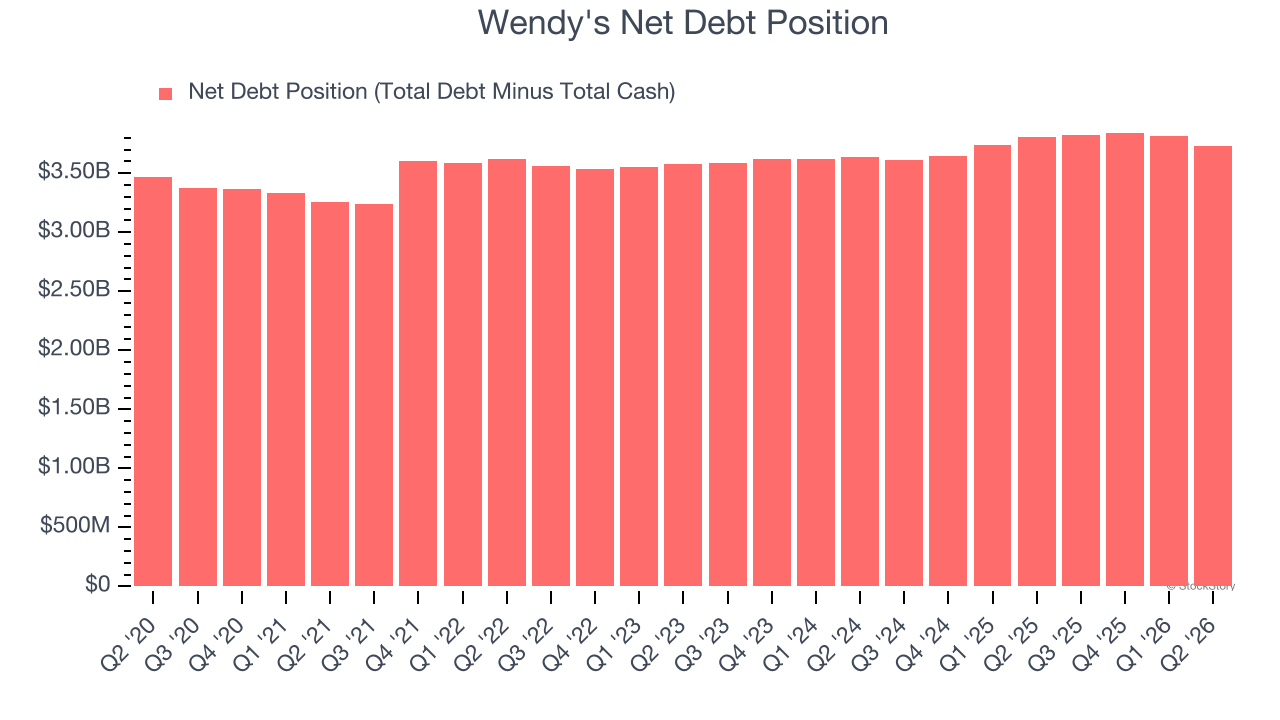
At this level of debt, incremental borrowing becomes increasingly expensive and credit agencies could downgrade the company’s rating if profitability falls. Wendy's could also be backed into a corner if the market turns unexpectedly – a situation we seek to avoid as investors in high-quality companies.
We hope Wendy's can improve its balance sheet and remain cautious until it increases its profitability or pays down its debt.
Final Judgment
Wendy's doesn’t pass our quality test. With its shares lagging the market recently, the stock trades at 15.6× forward P/E (or $7.49 per share). This valuation multiple is fair, but we don’t have much confidence in the company. There are more exciting stocks to buy at the moment. Let us point you toward the most entrenched endpoint security platform on the market.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.