RTX has followed the market’s trajectory closely, rising in tandem with the S&P 500 over the past six months. The stock has climbed by 11.1% to $195.17 per share while the index has gained 7.5%.
Is now a good time to buy RTX? Find out in our full research report, it’s free.
Why does RTX spark debate?
Originally focused on refrigeration technology, Raytheon (NSYE:RTX) provides a variety of products and services to the aerospace and defense industries.
Two things to like:
1. Core business firing on all cylinders
We can better understand defense contractors companies by analyzing their organic revenue. This metric gives visibility into RTX’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, RTX’s organic revenue averaged 11% year-on-year growth. This performance was impressive and shows it can expand quickly without relying on expensive (and risky) acquisitions. 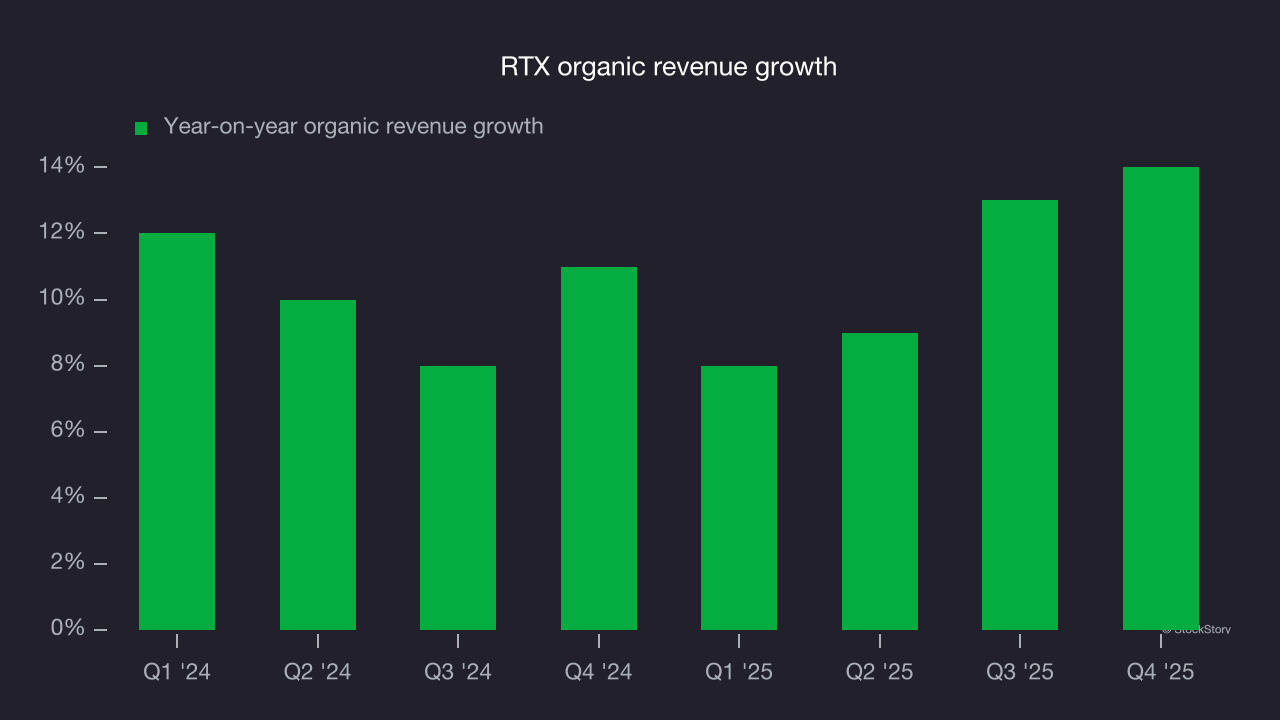
2. Increasing free cash flow margin juices financials
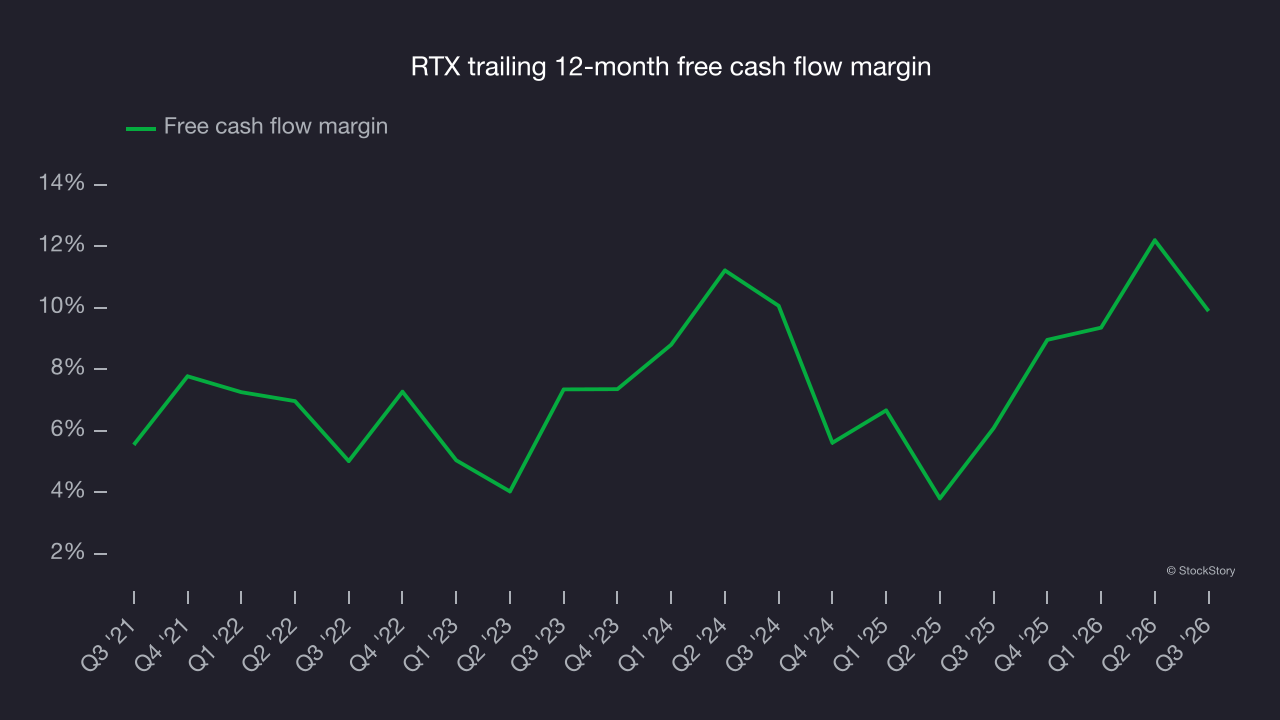
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
As you can see below, RTX’s margin expanded by 4.9 percentage points over the last five years. This shows the company is heading in the right direction, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. RTX’s free cash flow margin for the trailing 12 months was 9.9%.
One reason to be careful:
Previous growth initiatives haven’t impressed
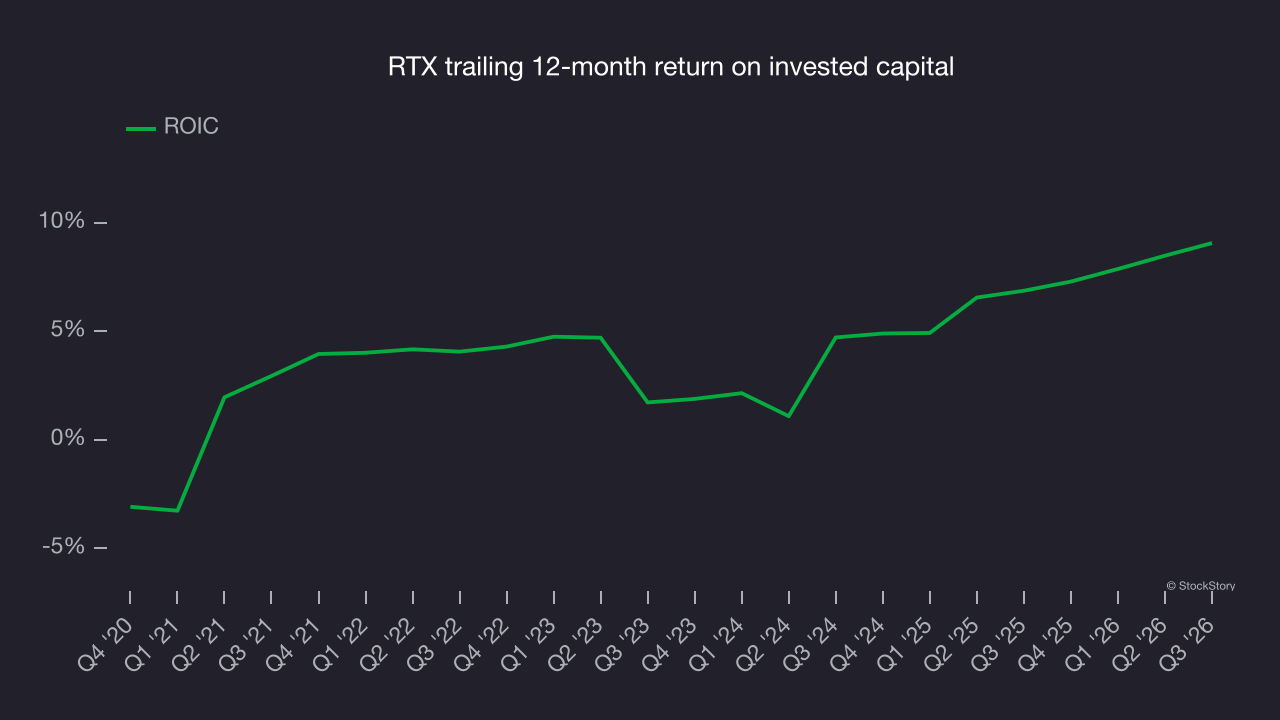
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
Although RTX has shown solid fundamentals lately, it historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 5.3%, somewhat low compared to the best industrials companies that consistently pump out 20%+.
Final judgment
RTX has huge potential even though it has some open questions. At $195.17 per share (or 25.4× forward P/E), is now the right time to buy the stock? See for yourself in our full research report, it’s free.
High-quality stocks for all market conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.